
 By
Yes, if you sell a service, hire nobody, hold no inventory and work from a desk you already own. That is the narrow answer to can i start a business with no money: opening can be almost free while the business still has bills.
The usual advice lists free tools and says anyone can launch tonight. It gets the first part right and skips the part that breaks launches: zero startup cash and zero working capital are different tests. A client can pay at 45 days, a refund can clear in week three, and the car can fail in the same month. The launch survived; the timing did not.
The costs that remain are predictable enough to plan for: registration, a bank account, insurance for the trade, phone and internet, a tax set-aside and living money while invoices age. Sort the idea into a cash tier, prove someone will pay before spending, and set a stop rule before optimism sets it for you.
Table of Contents
- Why Zero Dollars Usually Means Minimal Cash
- Low-Cost Business Models and What They Really Cost
- How to Prove Demand Before Spending Anything
- Costs You Cannot Safely Postpone
- Ways to Fund Early Expenses Without Expensive Debt
- When a No-Money Launch Stops Being Smart
- Decide Whether to Start This Month
Why Zero Dollars Usually Means Minimal Cash
A launch with no money works when the business begins as what the Census Bureau calls a nonemployer business, an operation with no paid employees. In 2024—the latest year of data released by the U.S. Census Bureau—there were approximately 32.0 million nonemployer businesses (31,985,874) that together generated roughly $1.86 trillion in receipts. Those are real trading firms, not ideas: the definition covers businesses without paid employees that have at least $1,000 in annual receipts ($1 or more in construction) and file a federal income-tax return
The typical shape is a laptop, a phone and a desk you already own.
None of that makes a launch expense-free. Registration, equipment, software, insurance, marketing, taxes and transaction fees can all appear before the first invoice is paid, and the Census figures don't promise otherwise. What they show is that entrepreneurship separates cleanly from hiring and from major capital investment. A founder can validate demand, land one customer and reinvest revenue long before payroll or a lease enters the picture.
The Distinction That Decides Most Launches
Most "start with nothing" content treats the problem as motivational. It isn't. The practical question is which costs the first sale forces you to carry and which ones you can postpone.
Zero startup cash means you didn't buy inventory, premises or software to open. Zero working capital means you have no money moving through the business while you wait to be paid. Almost nobody launches with both. Transport, insurance, a tax bill, a refund, an internet bill and your own living costs keep arriving whether or not the client has paid.
Three Cash Tiers for Any Business Idea
Place your idea in one of these before you read further, because the advice that follows differs by tier.
No-cash ideas. The work runs on a skill you already sell plus a phone and a laptop. Freelance writing, bookkeeping for two clients, tutoring, admin support, a virtual assistant retainer. The first sale needs your time and someone who already trusts you.
Low-cash ideas. A few hundred dollars covers registration, basic tools and insurance. Local cleaning, handyman work, mobile beauty, home baking under cottage-food rules. The money buys legitimacy and safety, not inventory.
Real-cash ideas. Stock, premises or a licence come before the first sale. A shop, a food truck, imported inventory, anything with a regulated qualification. These aren't no-money businesses and pretending otherwise is how people lose savings.
The Self-Check to Run Before You Read Further
Write down every cost the first sale requires. Materials, transport, a permit, a subscription, insurance, payment processing. Then mark each one as either covered by current income or needs money you don't have yet. If the second list is longer than your savings, you're in the wrong tier or the wrong model, and the next section is where you fix that.
Practical rule: if you can't name the exact cost of your first sale, you don't know your tier yet. Work it out on one page before spending anything.
Low-Cost Business Models and What They Really Cost
The table below is the reference I'd use to compare models. Price alone is the least interesting column.
| Model | Realistic Cash to Start | Main Early Cost | Time to First Payment | Refund or Stock Risk |
|---|---|---|---|---|
| Freelance writing, admin or design | $0–$100 | Software you may already own, portfolio time | 1–4 weeks | Low; scope disputes |
| Local cleaning or handyman service | $150–$600 | Supplies, insurance, vehicle use | 1–3 weeks | Low to moderate; property damage claims |
| Digital products (templates, guides) | $50–$300 | Design tools, hosting | 2–8 weeks | Low; long time before sales |
| Coaching or consulting | $0–$100 | Website, booking tool | 2–6 weeks | Low; depends on your network |
| Reselling secondhand goods | $200–$500 | Inventory, shipping supplies | 1–4 weeks per sale | Moderate; unsold stock |
| Dropshipping | $300–$1,500 | Ad spend, store platform | 2–6 weeks | High; ad costs and refund rate |
| Home food or baked goods | $300–$2,000 | Permits, equipment, packaging | 2–6 weeks | Moderate; permit rules and spoilage |
These ranges are typical planning estimates, and they move with country, city and platform. Treat them as a starting point for your own arithmetic, not a quote.
Two launches, two cash profiles. A freelance bookkeeper signs her first client using a spreadsheet and a free invoicing tool she already has, so her cash outlay is close to nothing and her first payment may arrive within two weeks of the invoice. A reseller of secondhand goods has to buy roughly $300 of stock before a single buyer sees it, then wait for the platform to release funds after delivery. Same "low-cost" label, completely different cash timing.
The Three Columns That Matter More Than Price
Cash to start tells you whether you can begin. The other two decide whether you survive the beginning.
Time to first payment is working capital in disguise. A model that pays in 10 days can be run on a thin float. A model that pays in 45 days needs savings, a deposit or a credit facility you'd rather not use.
What happens when a sale goes wrong is the exposure you can't see in the startup cost. A service business faces a scope dispute or a redo. A stock business faces unsold inventory. An ad-driven store faces paid clicks that never convert plus refunds against revenue you already spent.
If you're weighing a virtual assistant retainer against a product store, the retainer wins on cash timing almost every time. Here's a practical route into that model: make money online as a virtual assistant. The same logic applies to any service where the client pays before delivery. If your model depends on video or AI output and you're about to commit to a subscription, check AI video generator pricing first, because a monthly tool fee is working capital you can't get back.
Choose the model where the first payment can arrive within 14 days using something you already own. If it can't, you need a bigger buffer than the model suggests.
That 14-day rule is the strict version of the 30-day first-sale window in the checklist at the end. Use the strict number while you're choosing, and the looser one only when you're already selling.
How to Prove Demand Before Spending Anything
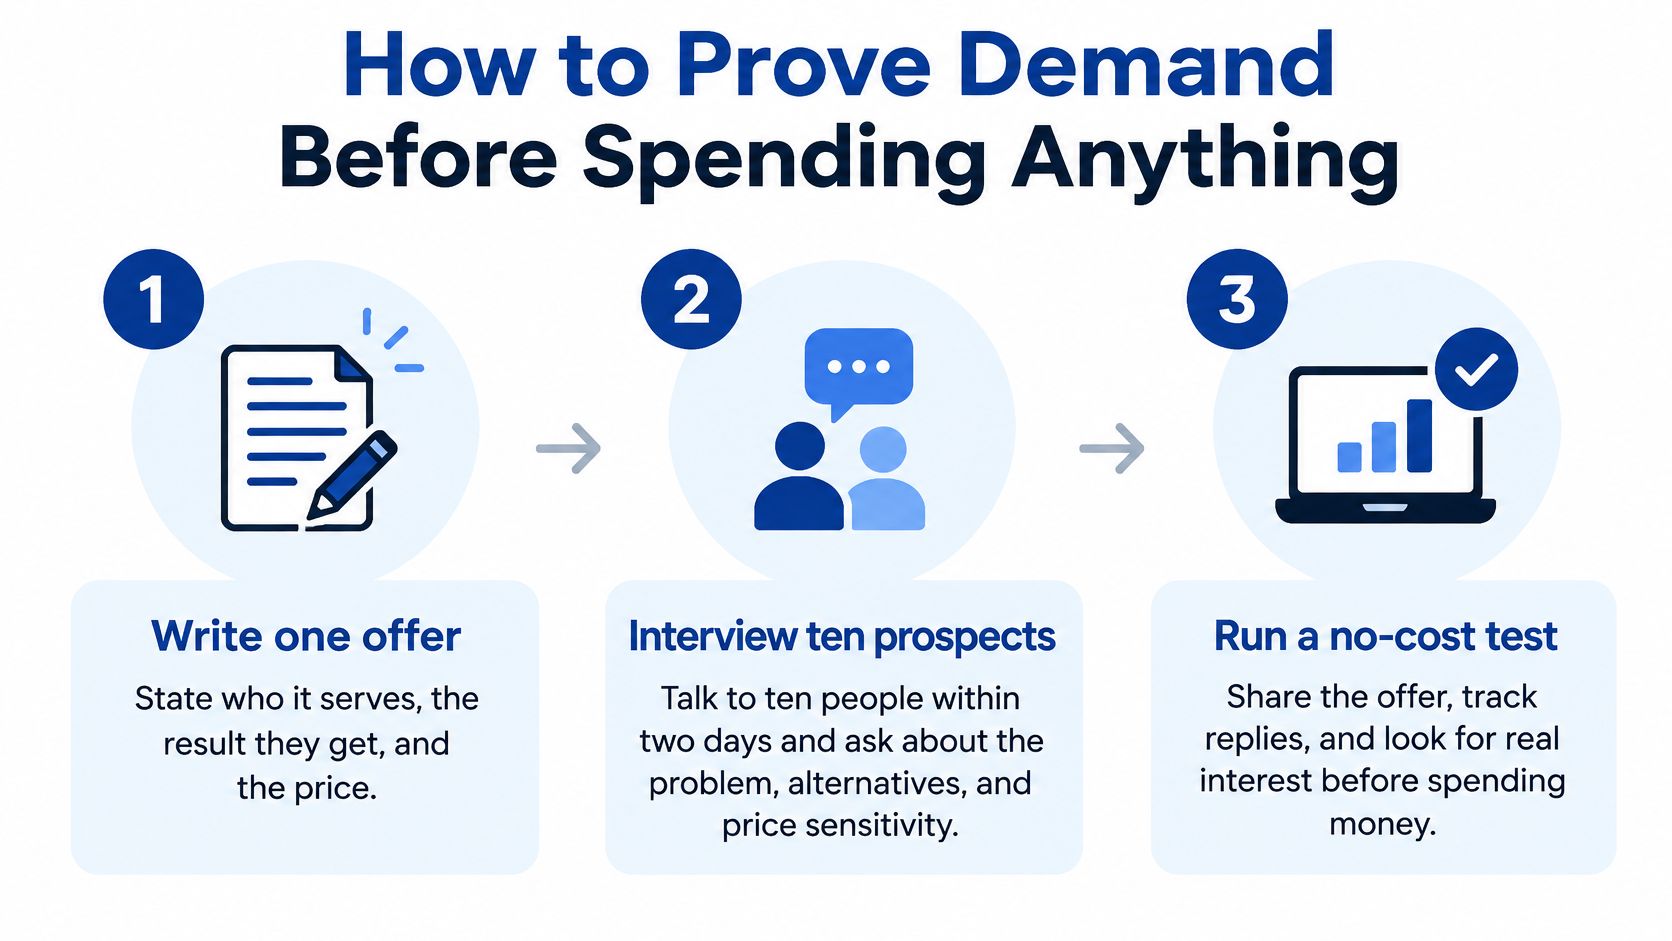
Demand proof is cheap. Everything after it is not, and the bill lands on working capital rather than startup costs. The six steps below move from conversation to cash without building anything first, and they protect the buffer you need for the costs that cannot wait.
The order matters because of what borrowing costs while demand is unproven. In 2025, 81% of surveyed U.S. small-business owners who had applied for a loan or credit line said affordable capital was difficult to access, and 51% said prevailing interest rates made borrowing unaffordable, according to the Goldman Sachs survey on small-business access to capital. The same survey found that 47% of owners who did not seek capital wanted to avoid debt. Borrowing against an unproven offer turns a cheap experiment into a payment schedule.
The Six-Step Demand Ladder
Write the offer in a single sentence. Who it serves, the result they get, and the price. Vague offers attract vague replies, and you can't test a paragraph of positioning.
Interview ten prospects within two weeks. Ask what they currently spend or lose on the problem, not whether the idea sounds good. Compliments cost nothing and predict nothing; current spending is evidence of a budget.
Ask for a commitment. A paid pilot, a deposit, or a signed letter of intent. If nobody commits, revise the offer before you build, buy, or borrow. This is the only step that separates interest from money, and it is what makes any later loan application sensible rather than hopeful.
Deliver the first order by hand. A spreadsheet, a shared document, a basic booking page. Manual delivery proves you can produce the result without a tool investment you might not need.
Calculate contribution margin on every sale. Price minus direct costs. A $60 fee with $12 of materials, transaction fees and shipping leaves $48 to cover your time and rebuild your float. If the number is thin, raise the price or cut the scope.
Reinvest only after two repeat or referred sales. A buyer who comes back or sends someone else is the first real signal the offer works, and that is the point where spending becomes rational. Spending earlier usually means borrowing to scale an offer that has not earned it.
Here's a short walkthrough of the same logic applied to a product idea.
Skipping steps produces predictable failures. Interviews without a commitment request produce encouragement. Delivery before a first sale produces inventory nobody asked for.
If you're at the product-choice stage and haven't settled what to test, this guide on validating demand before you launch covers how to narrow the field without buying inventory.
Before moving on, apply one last check. Count the unpaid hours it took to win that first commitment, and price them at a rate you would accept for your own time. If those hours plus direct costs consume the contribution margin from step 5, demand exists but the economics do not. Twenty hours of unpaid pitching is working capital in disguise, and it deserves the same scrutiny as cash.
Costs You Cannot Safely Postpone
Zero startup cash is not the same as zero working capital. The costs below stay with you whether or not the business earns anything this month, and each one carries a distinct consequence if you skip it.
| Cost | When It Applies | Typical Range | Risk if Skipped |
|---|---|---|---|
| Business name registration and licence | Before the first invoice | $50–$500 by location and trade | Fines, or unable to invoice or open an account |
| Separate business bank account | Before the first payment | $0–$30 per month | Mixed finances and tax errors |
| Liability insurance | Before working in client homes or on their property | $400–$1,200 per year | Uninsured claims can wipe out savings |
| Tax set-aside | From the first income | 20–30% of net income | Surprise tax bills |
| Phone and internet | Always | $30–$100 per month | Missed client contact |
| Refund or chargeback reserve | After the first sales | 5–10% of revenue | Cash gaps when refunds land |
| Personal living buffer | Until break-even | Three months of essential costs | Forced sales at a discount |
Ranges are typical estimates and shift with country, trade and region. Check your own jurisdiction's fees and licensing rules before you rely on any figure here.
Why Cash Flow Ends Most Launches
Among owners who pursued funding in 2025, only 36% secured any, and insufficient cash flow was the most frequently cited reason for rejection at 59%, according to Gallup and JPMorgan Chase research on small business growth. Lenders want to see money already moving through a business before they add more of it, which is why the buffer rows above matter more than the launch price.
That is a working-capital constraint, and the fix is an account that can absorb a bad month.
The tax set-aside and the refund reserve belong on the list even when the launch costs nothing. Tax money isn't yours the moment it lands, and a refund in month two can empty an account that looked healthy in month one.
How Big a Buffer You Actually Need
For a service model, the floor is one month of essential personal costs. You invoice, you deliver, you get paid, and a single month of cover bridges the gap.
Three months is the number to build toward. That absorbs a lost client, a slow quarter or a broken laptop without forcing you to discount.
Product models need more than either. Stock ties up cash before revenue, platforms hold funds after delivery, and returns arrive after you have spent the money. Same principle, larger float. A seller taking deposits still needs the refund reserve funded before the first order ships.
Now run the test. Total the rows that apply to your model, then compare that figure with the savings and client money already committed. A gap wider than one month of essentials on a service business means you hold off on spending.
New owners guess most often on the legal side. This walkthrough of legal requirements when you start a business covers registration and the compliance items that appear before your first invoice.
Skipping insurance is not a saving. It's a loan against your savings that you never agreed to.
Ways to Fund Early Expenses Without Expensive Debt
Start with how founders pay for launches. Personal money dominates by a wide margin, which tells you bootstrapping is the normal path, not a heroic exception.
Federal Reserve survey evidence reported that more than 70% of small and nascent businesses were started using personal savings or assets, compared with approximately 6% using a personal loan from a bank or savings institution, 3% using a personal or business credit card, and 3% using a business loan from a bank or savings institution. For a founder with no trading history and no credit record, that pattern is the practical baseline.
| Source | Typical Cost | Speed | Best Fit | Main Risk |
|---|---|---|---|---|
| Personal savings | No interest | Immediate | Small, low-risk first tests | Personal financial exposure |
| Customer deposit or prepayment | No interest | 1–3 weeks | Services with a defined scope | Refund obligations if work fails |
| Family or friend loan | Often 0%, if agreed | 1–4 weeks | Small amounts with written terms | Strained relationships |
| Grants | No repayment | Several months | Specific sectors or communities | Competitive and uncertain |
| Microloan from a community lender | Varies; check the APR | 2–8 weeks | Very small early costs | Application effort and sometimes a personal guarantee |
| SBA-backed microloan | Set by the lender within program limits | 1–3 months | Businesses with a written plan | Slow and document-heavy |
| Credit card | Often 20% APR or higher | Immediate | A short gap with a clear repayment plan | Interest compounds quickly |
Costs are approximate and must be checked against current lender terms for 2026.
Ranking the Options From Cheapest to Most Expensive
Customer money first. The cheapest funding on the table is a deposit a client pays before you start work. It costs no interest, it proves demand and it arrives before your costs do. That's why step 3 of the demand ladder matters more than any loan application.
Then your own savings, limited to what you can afford to lose, because a launched business can return nothing.
Then family and friends, in writing. Amount, repayment date, what happens if the business fails. Verbal arrangements are where relationships go bad.
Grants before debt where they fit. No repayment, but a competitive process and a long wait, so they suit planned costs rather than next week's bill.
Microloans from community lenders cover very small amounts when you have a written plan. The cost is documentation time and, often, a personal guarantee.
SBA-backed lending is a slower, heavier version of the same thing. Scale is real: in fiscal year 2024 the U.S. Small Business Administration supported 103,000 small-business financings with a total capital impact of $56 billion. It's a genuine channel for owners with a plan and patience.
Credit cards last. A high APR against a business with no repeat sales is the most expensive way to fund a guess, and balances grow while you're busy delivering.
How to Become Creditworthy With No History
Lenders read behaviour, so give them some. Open a separate business bank account and run every payment through it. Pay suppliers on the agreed date, even when it's inconvenient. Keep a clean record of client invoices and receipts. Apply for a small credit line only after repeat sales show the offer works, and ask for an amount you could repay from one month of normal revenue.
This is also where comparison helps. These start-up sources of financing compared put the same options side by side, and reviewing them before you apply saves a wasted application.
Borrowing should follow proof of demand, never replace it.
When a No-Money Launch Stops Being Smart
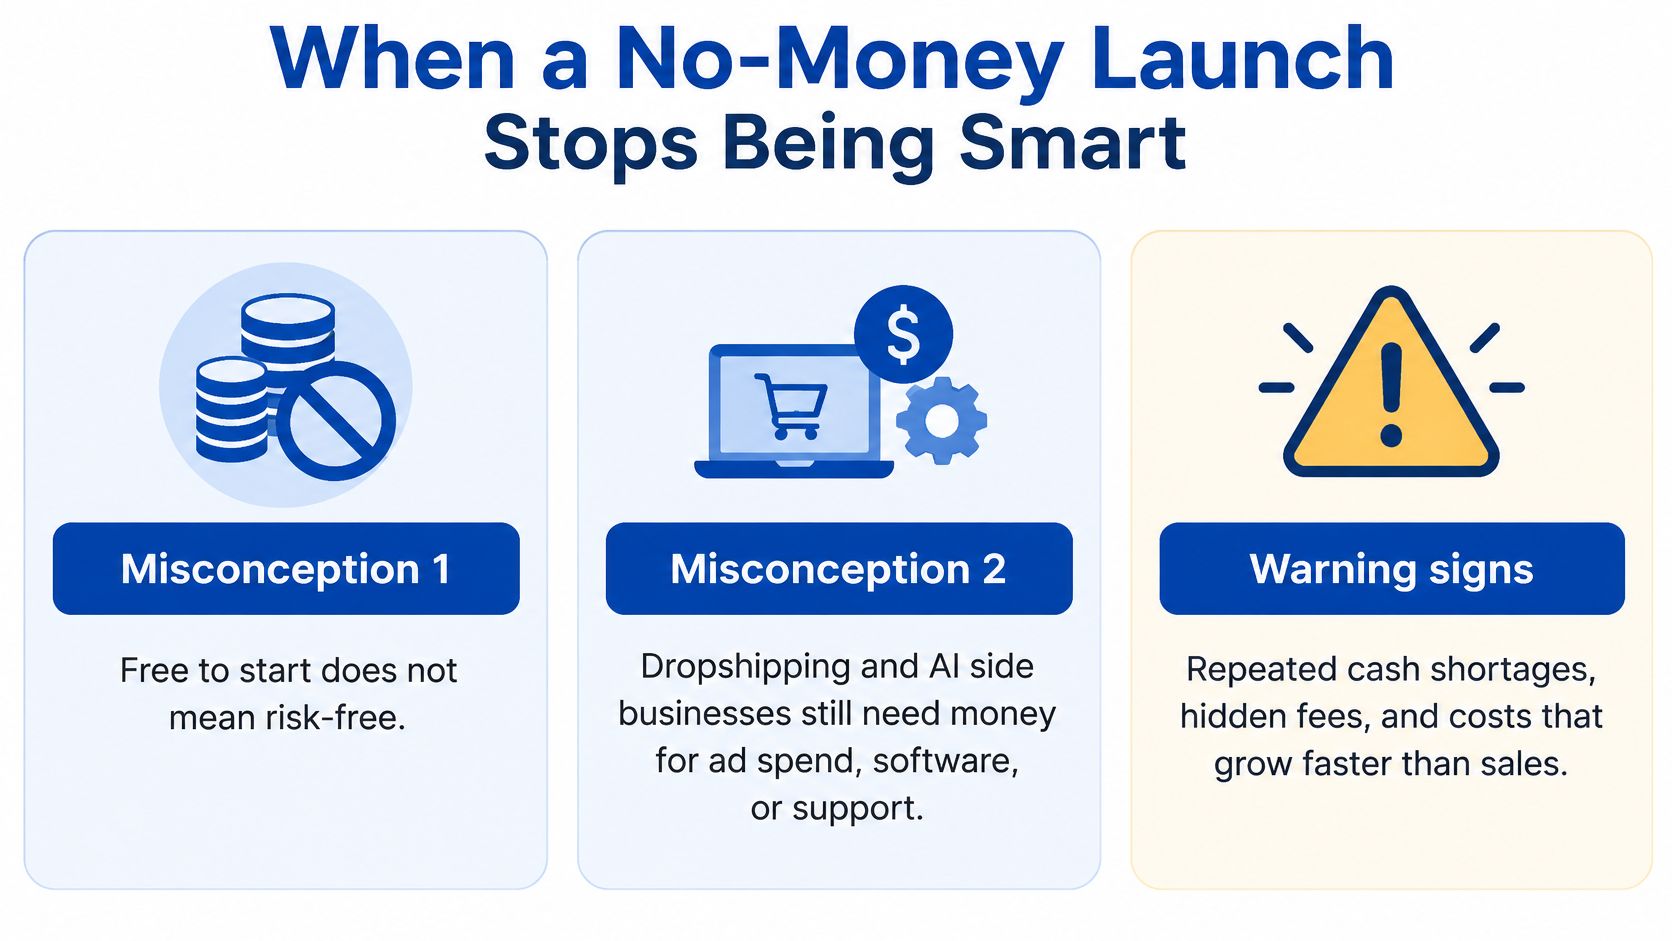
Bootstrapping has limits, and they arrive subtly. Three claims do most of the damage.
Three Claims That Cost People Money
"Free to start means risk-free." It doesn't. A launch can cost nothing and still expose you to refunds, damage claims and unpaid time. Exposure and outlay are different things.
"Dropshipping and AI side businesses need no money." Ad spend, store subscriptions, tool tiers and refunds often become the largest early cost in exactly these models. The software isn't the expense. Buying attention is.
"A fast first sale proves the business works." One sale proves someone bought once. Repeat and referred buyers prove the offer holds, and that's the evidence worth spending against.
A reseller illustrates the trap better than any warning list. Each batch sells, so the next batch goes on the card, bigger than the last. The balance grows faster than the profit because shipping, refunds and platform fees are paid from the same account, and nobody separated the two. The business looks busy and the founder is borrowing at 20% to fund it.
The Stop Signals and What to Do About Each
Personal savings drop below one month of essential costs (service model) or two months (product model). Pause all spending, invoice immediately, and collect what's owed before buying anything else. The three-month target is where you want to be; stop there.
The first ten customers pay late or not at all. Narrow the offer to buyers who pay upfront or on delivery, and add deposits to your terms.
A licence or specialist equipment is required before any revenue. Switch to a service version of the same skill, or delay the launch until the cost is funded.
Ad costs exceed contribution margin on every sale. Raise the price or stop advertising. Paid traffic that loses money per order is a subsidy you're paying to a platform.
Debt payments depend on sales you haven't made yet. Restructure now, before the next payment date, rather than funding the shortfall with more credit.
None of these signals means the idea is bad. They mean the funding method is wrong for the stage. A service model with lower exposure, run alongside the product idea, keeps cash coming in while you fix the margin.
The moment you're borrowing to cover costs the business already incurred, you're no longer bootstrapping. You're financing a loss.
Decide Whether to Start This Month
Five conditions, and I'd want all five before committing a month to this.
The first sale can happen within 30 days using skills and tools you already have.
The direct costs of that first sale are covered by current income or money a client has already committed.
A separate account and a tax set-aside are planned, not promised for later.
Registration and insurance for your location and trade are identified, with a number attached.
None of the stop signals above is active in your situation right now.
All five yes means start a 30-day demand test this week: one offer written, ten prospects interviewed, one commitment requested. One failure means fix that item first and test next month. That's not a delay, it's the cheapest correction available.
The next step is funding research matched to the model you picked. We published "Why SBA Funding Is the Best Option for SMEs" on September 10, 2021, which explains how SBA financing works for smaller firms. Read it as one publisher's perspective and confirm current program terms before applying, because a 2021 post won't reflect 2026 rules.
A business can start with almost no money. What it can't do is start with no cash for the costs the first sale cannot avoid.
Mega Income Stream covers exactly this ground for people launching without capital: earning online without upfront investment, freelancing through free profiles on platforms, selling digital products with no inventory, and building service income as a virtual assistant or a narrow consultant. If you want the funding routes, the cost worksheets and the no-investment business models in one place, visit Mega Income Stream and start with the model that matches your cash tier.



Comments