
 By
The economics of autonomous vehicle (AV) fleets in ride-sharing, which are expanding at a 54.2% CAGR, depend on getting rid of driver labor costs, which are now the biggest expense. Although switching to autonomous vehicles (AVs) promises high utilization (24/7 operation) and efficiency, it also comes with large human monitoring expenses and hefty capital expenditures, which could pose a challenge to profitability if occupancy rates are low.
Key Economic Drivers and Challenges
- Cost Structure Shift: The primary advantage is removing the driver, converting variable labor costs into fixed capital and maintenance expenses. However, operating an AV fleet is not cost-free; human remote supervisors are still required, with costs potentially ranging from $0.05 to $2.35 per mile depending on the ratio of supervisors to cars.
- Utilization and Efficiency: Autonomous fleets allow for 24/7 operations, potentially doubling utilization rates compared to conventional human-driven fleets.
- Capacity Management: While AVs can reduce required fleet sizes by up to 55% in certain shared scenarios, they may increase vehicle-kilometers traveled (VKT) by 6% to 23%, potentially worsening congestion if not properly optimized.
Market Dynamics
- Market Growth: The autonomous ride-sharing market is rapidly expanding, with an estimated valuation reaching over $1.3 billion as of 2024, driven by rising demand for, shared, and electric mobility.
- Key Cost Factors: High operating costs, such as maintenance and safety oversight, are critical factors in the economic viability of driverless taxi services.
- Impact on Pricing: The success of AV fleets depends on whether operating savings can be passed to consumers, with profitability tied closely to maintaining high occupancy rates, similar to the benefits seen in autonomous trucking with increased efficiency.
Over the past couple of years, autonomous vehicles have crossed an important threshold. This is no longer just a question of if the technology works, but whether the business model work and how it’ll be setup 1P vs 3P, with or without fleet managers, vehicle financing strategies, etc.
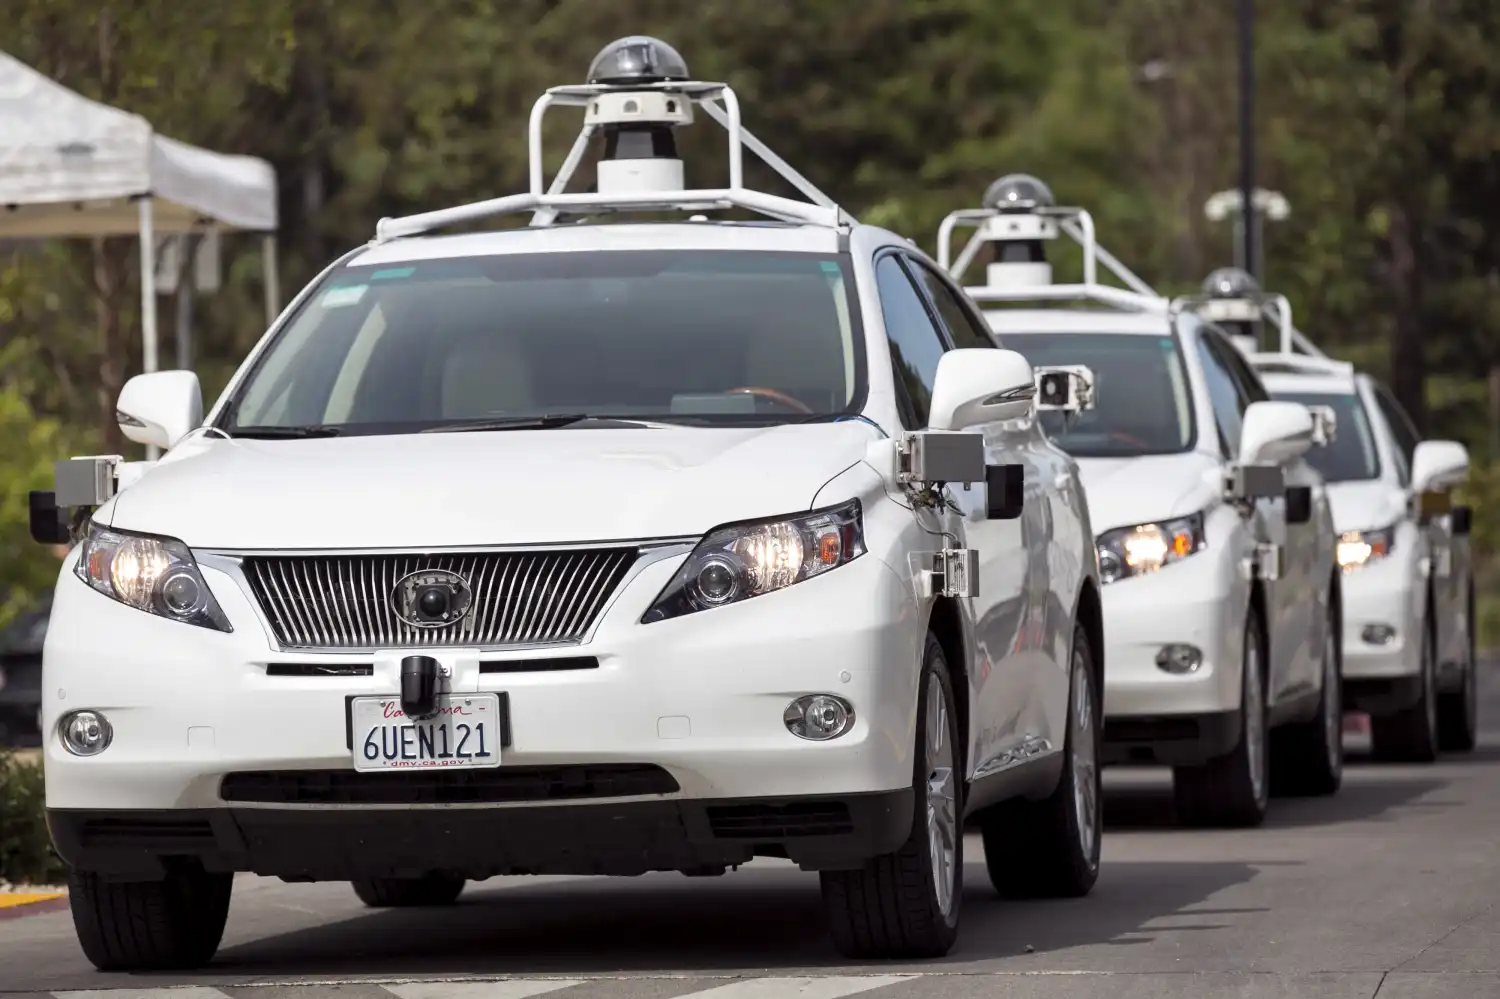
Waymo is operating real scale in San Francisco and Los Angeles, Tesla continues it’s 10 year history of signaling an imminent robotaxi launch, and Uber has been increasingly explicit that its long-term role may be demand aggregation rather than owning drivers or vehicles. Yet despite the growing volume of commentary, most discussions around autonomous rideshare economics remain hand-wavy. Phrases like “lower cost per mile,” “higher utilization,” or “no driver costs” get thrown around without ever fully connecting the dots.
At its core, AV Rideshare Economics is an interactive, bottom-up unit economics model for autonomous rideshare. It’s designed to let you toggle assumptions and immediately see how they flow through to per-trip economics, contribution margin, EBITDA, and operating profit. Rather than baking in a single “right” view of the world, the site is built around the idea that reasonable people will disagree on inputs and that the only productive way to debate those disagreements is to model them.
The framework supports both first-party (1P) and third-party (3P) operating structures, explicitly separating the economics of the autonomous vehicle provider, the marketplace/aggregator, and the fleet manager where relevant. The goal isn’t to predict winners, but to define the narrow corridors where each model actually works.
Who This Model Is For (and Isn’t)
This model is built for investors, operators, policymakers, and technologists who want to understand when autonomous rideshare works, not to argue that it must. It is not a valuation tool, a demand forecast, or a prediction of winners. It is a framework for pressure-testing assumptions.
Pricing & Marketplace Dynamics
Cost per Mile vs. Cost per Trip
One of the most common mistakes in autonomous rideshare discussions is mixing cost-per-mile logic with cost-per-trip pricing. Riders don’t buy miles; they buy trips. The model explicitly tracks both.
Cost per mile is driven by:
- Vehicle depreciation
- Energy
- Maintenance and cleaning
- Insurance and teleoperations
Cost per trip layers in:
- Average trip length
- Deadhead miles
- Marketplace fees and commissions
This distinction matters because short trips can look great on a per-mile basis while still being uneconomic on a per-trip basis once fixed costs are allocated. The model makes it very clear where that breakage happens.
3P Commission and Utilization Efficiency
The second pricing lens focuses on third-party marketplace dynamics. In a 3P model, the marketplace takes a commission, which at first glance looks dilutive. But higher utilization enabled by better demand aggregation can more than offset that take rate.
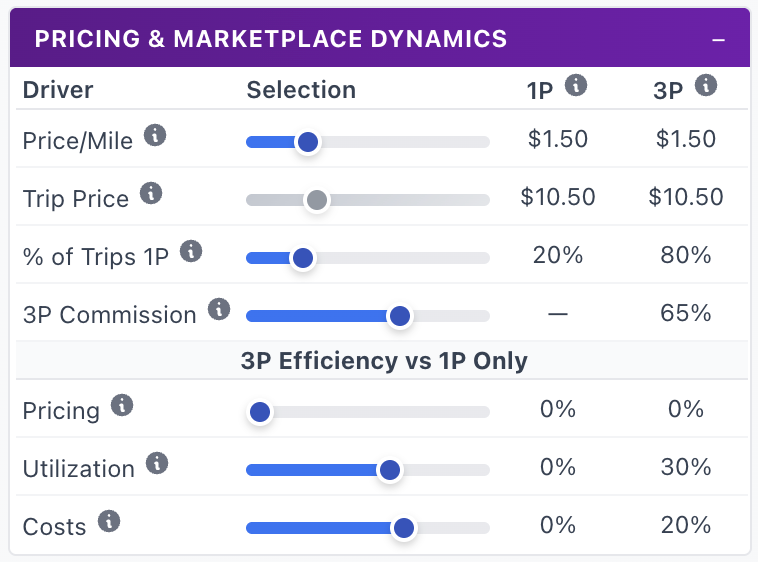
This is the crux of the argument from players like Uber: even if you give up 30–50% of gross bookings as a commission or revenue share to the 1P Fleet Operator, materially higher utilization and faster market expansion can improve absolute dollar economics. The model lets you explicitly test that claim by adjusting utilization uplifts, commission rates, and pricing power side by side.
Read Also: How Autonomous Vehicles Handle Extreme Weather Conditions
Early data and disclosures suggest higher effective utilization in Waymo-on-Uber cities relative to Waymo’s 1P-only operations. The big question is how much higher utilization and better unit costs can an aggregator like Uber or Lyft drive than a 1P solution from Waymo or Tesla?
Costs and Cost Allocation
A major design choice in the model is explicit cost allocation. Rather than lumping everything into a single margin line, costs are broken out and allocated based on what actually drives them.
Key cost buckets include:
- Energy
- Maintenance and repairs
- Cleaning
- Insurance
- Teleoperations
- Support
- Platform and overhead costs
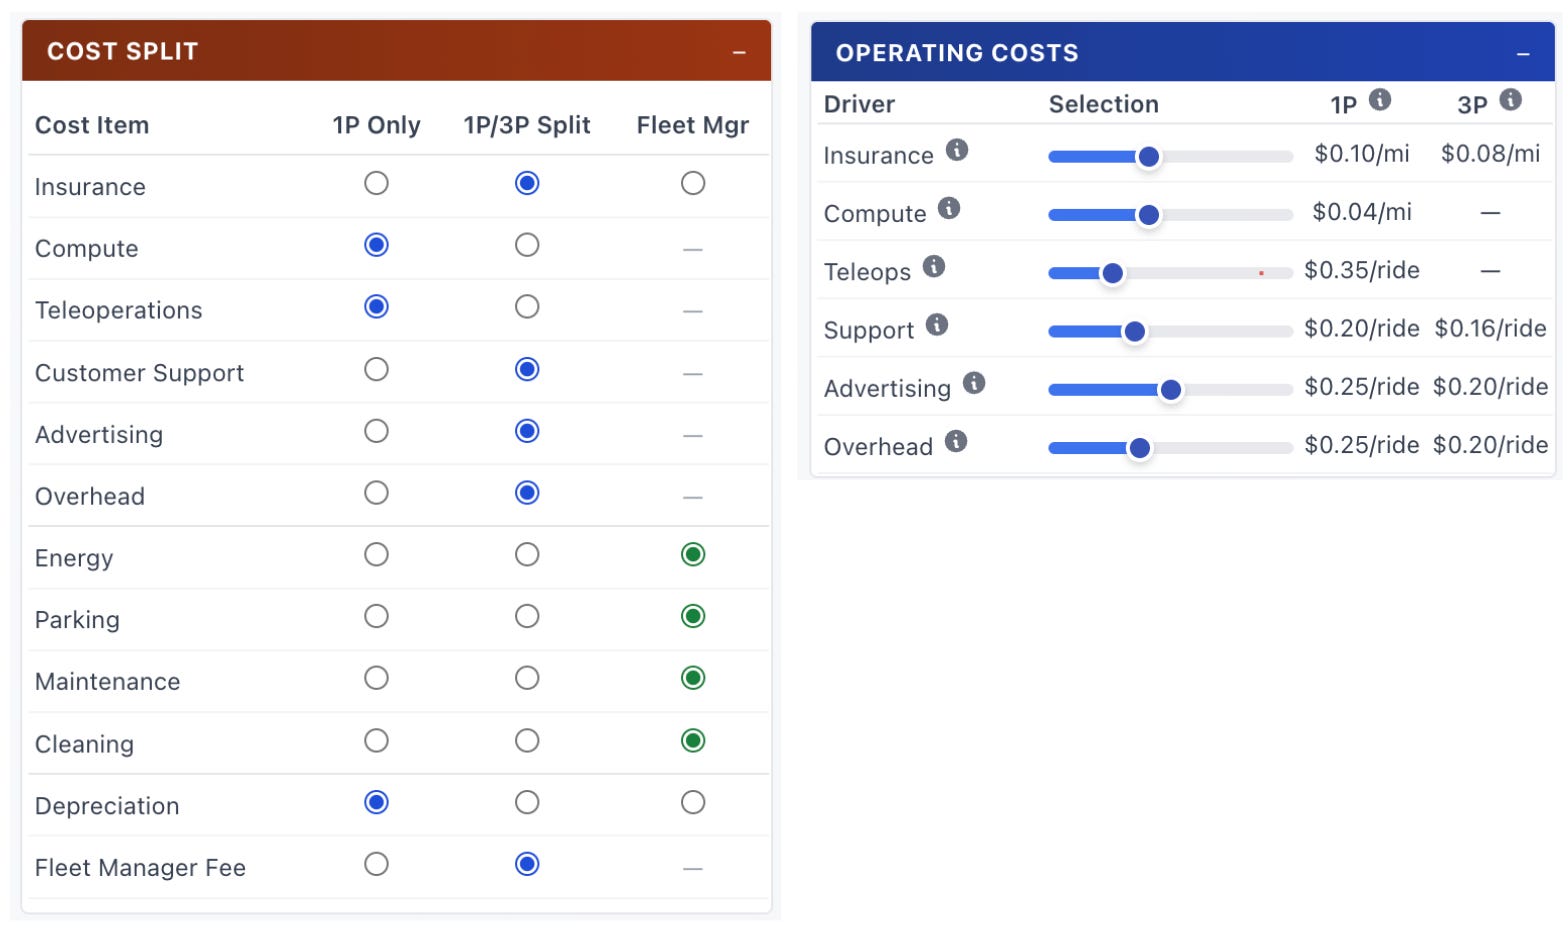
The allocation logic matters. Some costs scale with total system miles, others only with 1P-operated trips, and others are shared across the entire network. The model forces consistency so that per-trip and per-mile metrics reconcile cleanly to the annual P&L or per-trip or per-mile income statement. This avoids the common mistake of double-counting or under-allocating costs when mixing 1P and 3P operations.
Fleet Manager Economics
An area that’s often ignored in public discourse is the economics of the fleet manager. In many realistic scenarios, the autonomous technology provider will not directly manage charging, cleaning, parking, and maintenance. That role will sit with a fleet manager, earning a return on capital and operations.
The model explicitly separates fleet manager revenue and costs, allowing you to see:
- The management fee applies to 1P or 3P operator for their services
- Cost sliders for those costs under the responsibility of the Fleet Manager
- Sensitivity if you click the on/off toggle to remove the fleet manager from the model.
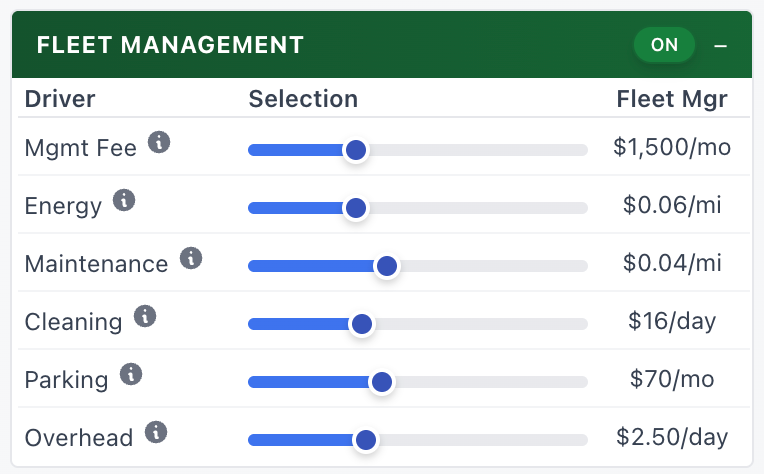
This helps frame an important question: are fleet managers a low-margin utility, or a structurally attractive layer once scale is reached? The answer depends heavily on utilization stability and cost discipline, both of which are easy to assume and hard to achieve.
Vehicle Financing Economics
Finally, the model incorporates vehicle financing, which is often glossed over despite being critical. Autonomous fleets are capital-intensive, and who finances the vehicles (and at what cost) materially changes outcomes.
You can toggle:
- Loan-to-value assumptions
- Interest rates
- Amortization periods
- Who bears the financing burden (1P vs fleet manager vs shared)
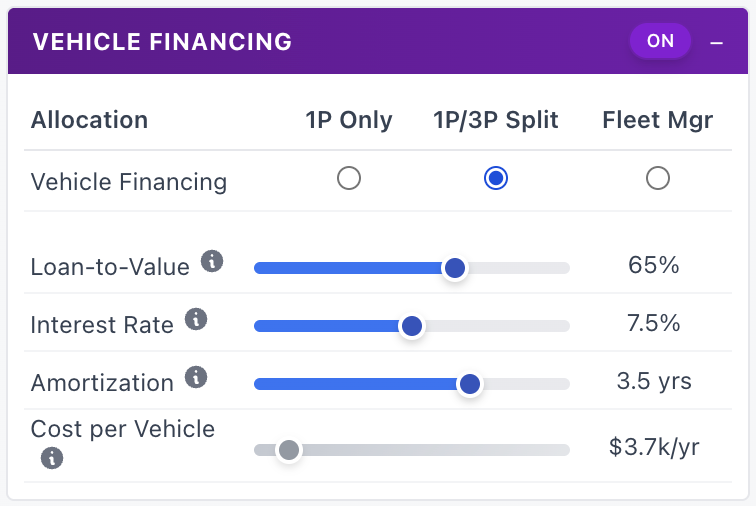
Interest expense flows below EBITDA and Operating Profit by design, reinforcing the distinction between operating leverage and capital structure. This makes it clear when a model “works” operationally but fails once financing reality is layered in. I’m still thinking through how I want to integrate cash flows into this and the capital structure of each player but that’s a future add-on.



Comments