
 By
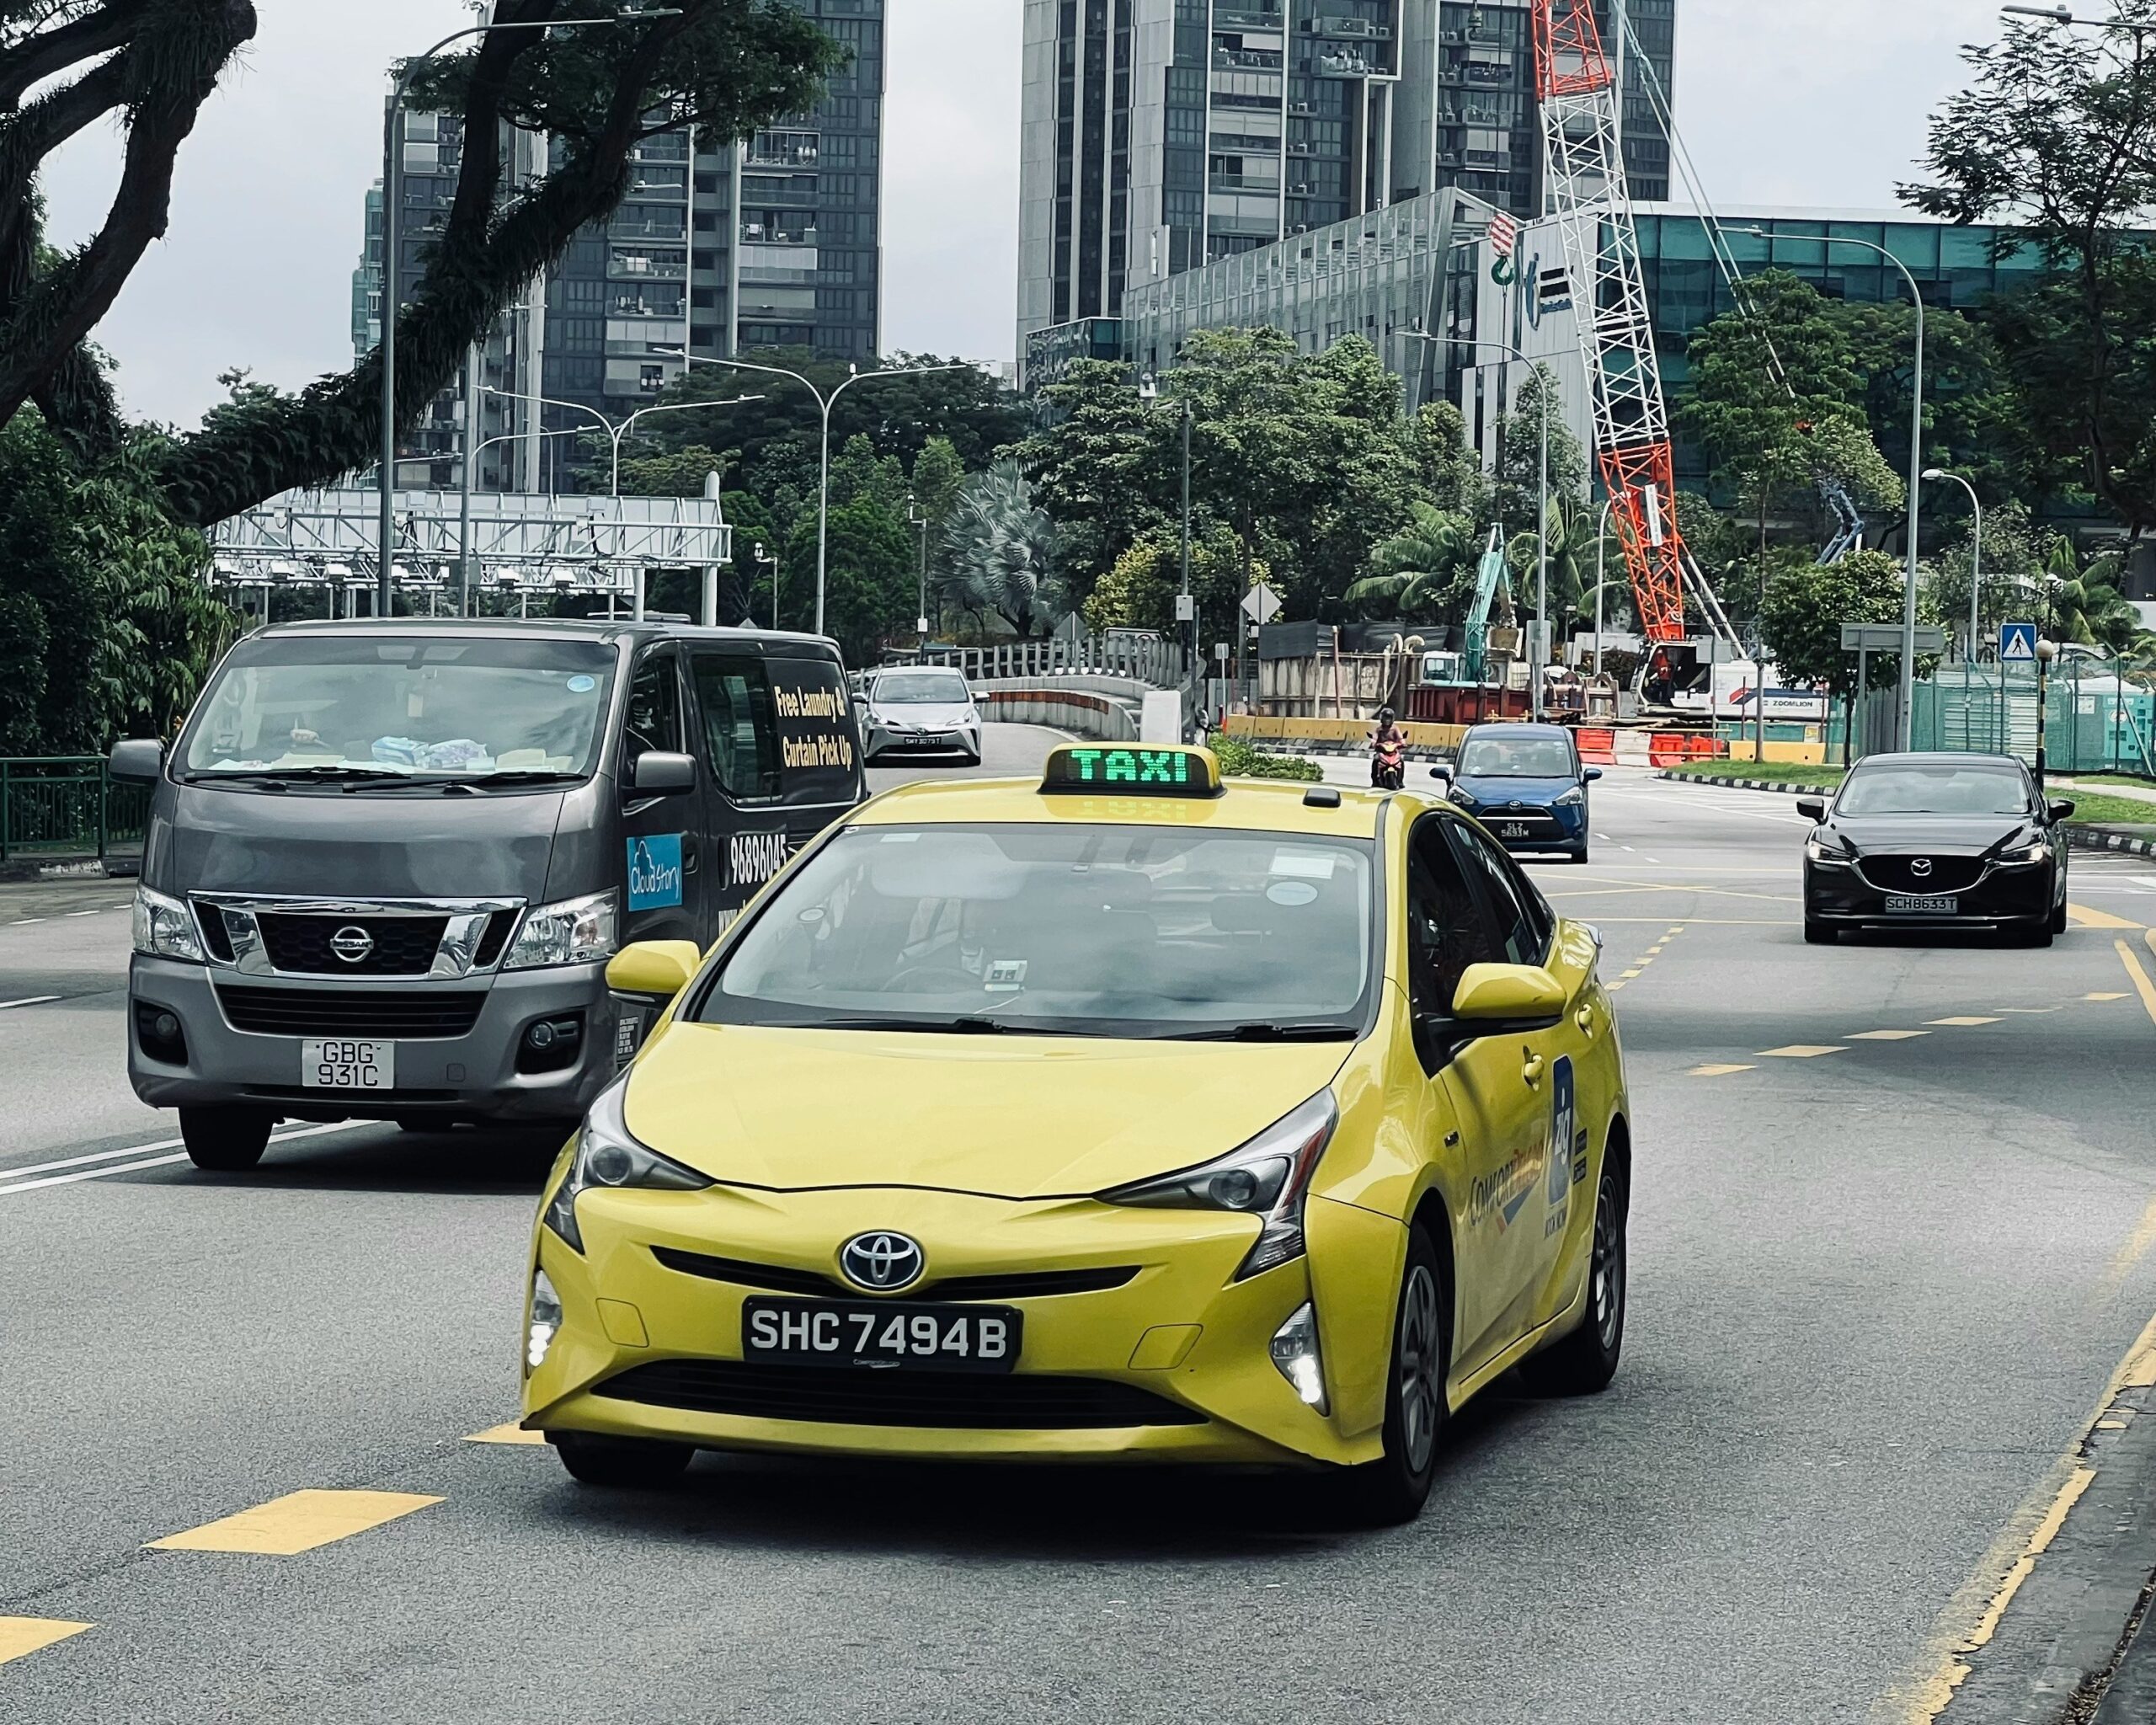
A strong driving month can make the work flexible and enjoyable. On the other hand, if the month is poor, the flip side of the model is soon apparent: the car still has expenses, the bills still come in, and the income from the platform does not wait for conditions to improve.
In this regard, the low fare months are more important than many drivers realize. In Singapore, Grab drivers face conditions during months with softer demand, tougher competition, weather, pricing pressures, and seasonality, which affect income without increasing costs. However, the personal loan comes in handy during the tougher months, provided the driver uses it appropriately and for the right purpose. The issue is not the availability of the loan, but the driver’s ability to use it without getting into trouble once the tough month ends.
When Fare Drops Disrupt Cash Flow
- Low-Fare Months Change Everything Fast
Gig income may appear secure when viewed from a distance, but the driver is aware that the situation can change quickly. A month that begins with normal conditions may deteriorate due to a drop in incentives, a decline in fares, a drop in the number of riders, or a rise in the number of drivers on the road. While the drop in income is a problem, the drop in expenses is not as pronounced as Rental, fuel, ERP, parking, and other expenses remain the same, which is why low-fare months are a problem.
This is not just a budgeting problem; it has serious consequences. For full-time drivers, a low-fare month is a problem that affects access to the vehicle, working hours, and a range of other issues that carry over into the next month as well. Cash flow is the driver’s work, and when this is compromised, the driver is no longer in charge of his or her income; the driver is now in charge of the continuity of the work.
- Fixed Costs Do Not Wait
The central problem for Grab drivers during slower months is that most major expenses are fixed or only partly flexible. Vehicle rental remains due. Fuel may fall slightly if fewer trips are taken, but it does not disappear. Insurance obligations, personal bills, debt repayments, and family expenses continue regardless of whether conditions are favorable. A driver may cut back where possible, yet the basic financial structure remains largely unchanged.
That is where a Taxi Driver Loan can enter the conversation as a cash-flow tool rather than a long-term lifestyle decision. Used carefully, it can help a driver bridge a weak period without missing rental commitments, falling behind on urgent bills, or taking the vehicle off the road at the worst possible time. The role of financing is not to mask the slowdown. It is to prevent a temporary dip from turning into a more damaging financial slide.
- Timing Matters More Than Urgency
The issue is that many drivers tend to wait too long before deciding whether financing is needed. This is because they tend to hope that the next week will turn out better, or that a few peak days will make up for the lackluster days. This strategy sometimes pays off, and sometimes it does not. By the time the driver decides to look for financing, overdue payments, loss of operating room, or issues associated with the vehicle will have set in, and this will affect the ability to make the right decisions and compare properly.
The best way to handle this is to evaluate the situation early enough. For instance, when the conditions for low fares are evident and impacting the cash flow, the driver needs to evaluate the gap before it becomes a crisis. This is not the same as suggesting that the driver should borrow money at the first sign of a slow week; rather, it is recognizing that financing is best used as a short-term solution rather than a last resort.
- Borrowing Works Only With Discipline
The personal loan will help during a bad month, but only when the amount borrowed corresponds to a real need to operate. The risk is that the money is borrowed too broadly. The driver is borrowing money not only for rental, fuel, and immediate needs but also for other wants and short-term spending habits. The bad month will pass, but the debt will linger.
Those who manage their finances effectively will understand the purpose of the borrowed money. The exact amount needed will be borrowed; the amount needed to operate will be considered, and the borrowed amount will not exceed that amount. This is the difference between using money strategically and emotionally. During low-fare months, discipline is more important than hope. The borrowed money will solve the problem, not make it larger by extending the payoff time.
- Income Volatility Changes Lending Needs
Grab drivers don’t follow the income pattern that many traditional lenders would like to see. Their income is subject to change depending on the demand, timing, route, and incentive schemes. The income of a salaried employee might be more predictable and easier to document, but that does not mean the driver is incapable of repaying the loan. This simply means the driver’s income needs to be assessed differently. This is important because drivers’ financing needs in the gig economy are driven by volatility, not by lack of income.
That is the main reason drivers seek financing solutions that account for their flexible income patterns. The loan’s usability is not necessarily driven by the speed of financing. Rather, the loan’s usability depends on whether the financing structure accounts for the driver’s income reality. The financing’s usability might be impaired if the repayment schedule does not account for the driver’s income reality. This is because the driver’s income in the ride-hailing business is functional but irregular, especially during off-peak hours.
- Vehicle Continuity Protects Earning Power
For many Grab drivers, the vehicle is the very foundation of their income. If rental payments fall behind or vehicle maintenance is neglected due to a lack of cash, the situation could deteriorate further. A Grab driver whose payments fall behind will lose time on the road, lose access to the vehicle, or experience increased stress levels that reduce their ability to earn money. This is when a short-term cash issue begins to affect the ability to earn money itself.
This is one of the stronger arguments for short-term financing. The need for a personal loan is clear when it will help the Grab driver maintain vehicle continuity during a difficult period. This means keeping rental payments up to date, addressing any urgent vehicle repair needs, ensuring insurance payments are made on time, and addressing any other transportation needs to ensure the Grab driver remains active and able to earn money. The argument is simple: financing is needed to ensure the Grab driver can continue to earn rather than merely spend.
- Repayment Must Match Real Conditions
Approval, however, is only the starting point of a borrowing decision. The key issue is whether the repayment remains viable when the pressure has subsided. The driver might feel relieved when the funds are approved, but this feeling quickly wears off when installments are too large relative to normal earnings. This is why low-fare borrowing should be based on normal monthly repayment capacity, rather than the hope that the next month might be strong.
A good borrowing decision assumes normal conditions, not ideal ones. Drivers need to consider how much they can repay in a typical month and whether they can still afford it when demand is slow for longer than expected. This minimizes the risk of curing a poor month by ruining the next three. Financing has a place, but only when it is compatible with how the driver really earns
Loans Help Most When Used Carefully
Low-fare months, therefore, pose a problem for Grab’s drivers. Their earnings decline rapidly, while their expense structure does not change significantly. For this reason, personal loans can prove to be useful for the ride-hailing market in Singapore. They can ensure the vehicle’s continuity, address immediate needs, and provide the necessary space for drivers to address the problem without risking business failure.
The practical application, however, is that the entire financing system must operate with precision. That is, the personal loan must address the actual gap, reflect the actual repayment capacity, and preserve earnings capacity rather than increase unnecessary expenditure. Low-fare months, for instance, are not uncommon for Grab’s drivers. What is important, however, is that the entire system must operate with precision. That is, the low-fare months must address the need to provide sufficient room for the entire system without increasing the cost of the problem.




Comments