
 By
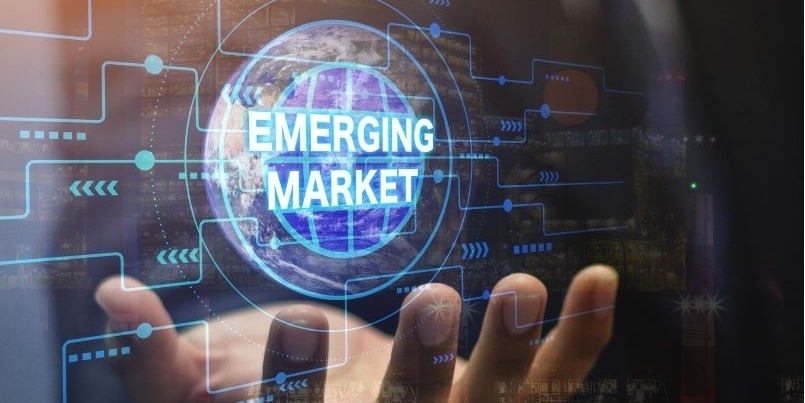
With better access to financial services, international markets, and education, the emergence of the digital economy presents emerging nations with substantial prospects for economic growth, job creation, and poverty alleviation. But there are drawbacks as well, like the requirement for robust institutional quality, infrastructure development, and cybersecurity. Digital transformation can give emerging economies leapfrogging possibilities by generating new business models and enabling certain sectors to skip conventional stages of development.
Opportunities for emerging markets
- Economic growth and job creation: Digitalization drives economic growth by boosting productivity and creating new jobs in sectors like tech and e-commerce.
- Market access: E-commerce and digital platforms provide entrepreneurs and small businesses with access to both regional and global markets, often with lower startup costs.
- Financial inclusion: Mobile banking and digital payment systems provide access to financial services for unbanked populations, fostering economic participation and empowerment.
- Improved services: Online learning platforms and telemedicine improve access to education and healthcare, especially in remote or underserved areas.
- Efficiency and innovation: Digital technologies can make societies more efficient and allow emerging markets to “leapfrog” older technologies and infrastructure.
- Empowerment: The digital economy has particular potential to empower women and improve their livelihoods through new economic opportunities.
Challenges for emerging markets
- Infrastructure: A lack of adequate digital infrastructure, such as reliable internet access, is a major barrier.
- Policy and regulation: Weak institutional quality and a lack of supportive policies can hinder the gains from digitalization.
- Cybersecurity: A strong national cybersecurity framework is essential to build trust and protect the digital economy from evolving threats.
- Skills gap: A shortage of skilled workers can limit a country’s ability to capitalize on digital transformation.
- Critical minerals: The growing demand for minerals used in digital devices can create new economic opportunities for resource-rich countries, but without moving up the value chain, it risks deepening commodity dependence and environmental issues.
Emerging economies are now the global economy’s engine, reshaping industries and upending conventions, rather than its future. According to the International Monetary Fund (IMF), these dynamic regions would be responsible for more than 60% of all global economic development by 2030. Countries like Brazil, India, and Nigeria are in a position to change the laws of international trade because of their fast growing middle classes and energetic, young populations. These markets are innovation hotspots full with unrealized potential, not just expanding customer bases.
What makes this prospect possible? technology. Technology is dismantling conventional boundaries, from mobile banking solutions that transform financial inclusion to e-commerce platforms that link companies with unexplored markets. Businesses are able to scale more quickly and intelligently thanks to it, turning obstacles into profitable possibilities. These developments act as change agents, enabling small businesses to reshape their growth trajectory and prosper in areas that were previously thought to be too difficult to join.
However, technology is not just useful for enterprises. It is changing socioeconomic environments and providing young people with new opportunities for entrepreneurship, skill development, and employment. Due to the democratization of access to international markets brought about by mobile technology and extensive internet connectivity, young entrepreneurs are now able to establish firms that were unimaginable ten years ago. Using Africa as an example, the International Finance Corporation (IFC) projects that the continent’s digital economy would grow from $180 billion in 2025 to an astounding $712 billion in GDP by 2050. This indicates a profound change in the balance of economic power.
Businesses that have the guts to enter these developing industries stand to gain a great deal, but only if they fully utilize technology. These areas are paving the way for a new era of international trade rather than waiting for approval to innovate.
How Technology Can Be the Catalyst for Growth in Emerging Markets
By expanding access to improved employment possibilities and fostering skill development, technology has unparalleled potential to revolutionize emerging markets. An example? Information technology accounted for 23.68% of the MSCI Emerging Markets Index as of January 31, 2025. This rapid climbing trend highlights the increasing importance of technology as a factor propelling economic development in these areas.
Read Also: The Future of Disruptive Tech: Emerging Trends and Innovations
The rapid spread of smartphones and internet access in emerging markets is a defining factor behind this tech-led transformation. Take Africa, where 72% of the population regularly uses mobile phones, and there are more than 300 million mobile money accounts, making it the largest hub for mobile payments globally. Likewise, in Latin America, smartphones accounted for 80% of all mobile connections in 2023 – and this figure is expected to climb to 92% by 2030.
These digital milestones aren’t just numbers; they’re foundational to economic growth. However, for technology to make the most impact, it must be accessible to as many people as possible – which is why it needs to be built with small businesses in mind.
Small and medium-sized enterprises (SMEs) are the backbone of economies in emerging markets. Across Africa, SMEs account for more than 90% of all enterprises and support over 80% of jobs. A similar story plays out in Latin America and the Caribbean, where SMEs form 99.5% of businesses, employ 60% of the workforce, and contribute 25% of GDP.
Yet despite their enormous economic significance, SMEs in these regions are often left behind when it comes to accessing the technology and resources they need to thrive. The reality is that the latest advancements in tech infrastructure and investment are often priced out of their reach, favoring multinationals and larger enterprises. This barrier limits the transformative potential of digital innovation for smaller players – and by extension, for the economies that depend on them.
To bridge the gap, technology must start working for SMEs. This begins with accessible digital platforms that connect local producers to global brands and distributors or link smaller retailers with larger suppliers. Such solutions create seamless supply chains and open up profitable opportunities for smaller businesses. The future of emerging markets lies in empowering SMEs with the right tools to compete, grow, and reimagine their role on the global stage.
Emerging Markets are Full of Opportunities
Over the next two decades, emerging markets are expected to be the engines of global growth. According to S&P Global, emerging economies are projected to average a 4.06% GDP growth rate through 2035 (compared to 1.59% for advanced economies) and are expected to contribute approximately 65% of global economic growth by 2035. These aren’t future possibilities: the shift is already in motion. Over the past 15 years, these markets have accounted for nearly two-thirds of global GDP growth and more than half of all new consumption.
At the core of this explosive growth lies rapid urbanization. Over the past two decades, the consumer class in emerging markets has doubled to 2.4 billion people. This shift isn’t just demographic; it’s economic. Additionally, in 2024, emerging and developing economies accounted for over 80% of the increase in global energy demand, which marks emerging-market consumers as a dominant force in the global economy, as they already make up most of the demand in many product categories like white goods and electronics. These markets don’t only follow trends: increasingly, they set them.
Another key factor behind the impressive potential of emerging markets is its large youth population. For example, in Africa, 60% of the population is under 25 – by 2050, one in four people on the planet will be African. Similarly, in Latin America, young people between the ages of 15 and 24 make up 20% of the population, the largest proportion of young people ever in the region’s history.
This youth surge, paired with unprecedented access to technology, could transform these continents into global power hubs. But here’s the catch. A young, growing population is only an advantage if it’s harnessed effectively. If these billions of youths are equipped with jobs and opportunities, the result is an economic transformation powered by rising incomes, increased spending, and prosperity all around. Ignore them, and the numbers invert. High unemployment and underemployment among youth can become a demographic time bomb, leading to possible instability and unrest.
Right now, many emerging markets are facing the latter. Youth unemployment rates remain alarmingly high. On average, they’re double the broader workforce. Latin America, for example, paints a stark picture. Youth face higher unemployment despite being better educated than previous generations and often settle for lower wages when employed.
Emerging markets urgently need innovative solutions to empower these young populations and unlock their full potential. The opportunity here is colossal. Imagine the impact if these millions of young people were contributors to their local economies, driving demand, innovation, and growth. Powered by technology, emerging economies could transform this untapped force into the engine driving the next wave of global prosperity.
The bold reality is this: the future of the global economy hinges on how emerging markets engage with their young population and ride the crest of urbanization. Ignore them, and you risk economic and social disruption. Empower them, and the possibilities are boundless.
Digital Divide
While the digital economy has opened up many potential growth opportunities, the so-called global digital divide remains. The capacity and quality of internet and mobile phone network coverage in many emerging markets still lags behind more advanced economies. Closing this gap can be challenging in countries with lower rates of urbanisation, as this complicates the extension of physical network infrastructure.
Alongside the requisite investment in hard infrastructure, there is a need for policymakers to put in place the legislative and institutional frameworks necessary to sustain growth. The Gulf states have been among the most forward-looking in this regard. In countries such as the UAE the digitisation of public services, coupled with the implementation of a favourable regulatory environment, is driving the transition, while also helping to support digital innovation across the economy.
Mobile Banking
Building on the success of earlier pilot projects in Africa and elsewhere, Kenyan mobile network operator Safaricom brought M-Pesa to market in 2007, in partnership with Vodafone. This service allows anyone with a basic mobile phone to use it as an electronic wallet and transfer money to others, pay utility bills, deposit and withdraw funds via agents, and even access microcredit. This mobile money system has brought financial services to large swathes of the previously unbanked population.
This coincided with a surge in mobile phone subscriptions in the country, from 30 per 100 people in 2007 to 86 by 2017, according to the UN’s International Telecommunication Union (ITU). By early 2019 the service had garnered 21m users in Kenya alone and was processing over 1.7bn transactions per year in the country. The platform has also seen success in neighbouring Tanzania, as well as in countries like Egypt and Afghanistan. The M-Pesa model has since spread to other countries, with similar platforms having been launched worldwide.
In March 2020 Safaricom implemented a 90-day fee waiver on M-Pesa transactions to reduce the use of cash during the Covid-19 crisis. The following month Peter Ndegwa, CEO of Safaricom, told local media that the company had seen a surge in data traffic and predicted that M-Pesa could see increased usage as customers opt for digital payments during the pandemic.
The proliferation of smartphones is making it possible for financial service providers to reach more customers in developing nations with comparatively inadequate ICT infrastructure and few bank branches. Furthermore, the marginal cost of each new customer is significantly lower than that of physical infrastructure once the initial investment in creating a digital platform is made.



Comments