
 By
The artificial intelligence boom is creating one of the largest technology infrastructure build-outs in modern history. Companies are spending billions of dollars on data centers, GPUs, networking equipment, power generation and cooling systems to support the rapid growth of generative AI.
That naturally raises an important question: Is today’s AI infrastructure boom another dot-com bubble?
The comparison is useful—but incomplete.
During the late 1990s and early 2000s, investors poured money into internet companies and telecommunications networks in anticipation of explosive online demand. Much of that infrastructure eventually proved valuable, but the investment cycle became excessive. The dot-com crash wiped out enormous amounts of equity value, while telecom companies were left with debt and excess network capacity.
AI infrastructure has some striking similarities. It also has important differences: today’s spending is being led to a large extent by highly profitable technology companies, AI services already generate substantial revenue, and the infrastructure being built has immediate commercial applications.
The bigger question is therefore not whether AI infrastructure will be useful. It almost certainly will. The question is whether today’s investment is being made at a pace that future AI revenues can justify.
AI Infrastructure vs. Dot-Com Infrastructure at a Glance
| Factor | Dot-Com Era | AI Infrastructure Boom |
|---|---|---|
| Main investment | Fiber-optic networks, telecom equipment, servers | GPUs, data centers, networking, power and cooling |
| Peak period | Roughly 1998–2000 | 2023–present |
| Primary demand thesis | Internet adoption | Generative AI and accelerated computing |
| Major investors | Telecom companies, startups, venture capital | Hyperscalers, AI companies, chipmakers, institutional investors |
| Financing | Heavy corporate debt and equity speculation | Corporate cash flow, debt, leases, partnerships and equity |
| Infrastructure risk | Excess bandwidth | Excess compute capacity |
| Technology depreciation | Relatively slow for fiber | Rapid for AI accelerators |
| End-user revenue | Often speculative | Already significant and growing |
| Major concern | Overcapacity and leverage | ROI, power constraints and utilization |
| Long-term legacy | Internet infrastructure remained valuable | AI infrastructure could become foundational technology |
The historical parallel is therefore strongest when looking at capital intensity and expectations, rather than simply comparing company valuations.
The Scale of Today’s AI Infrastructure Spending
The numbers are extraordinary. McKinsey estimates that global data center capital spending could reach $7 trillion by 2030, driven heavily by AI and the resulting demand for computing capacity. Its research also estimates that data centers could require approximately $6.7 trillion in cumulative capital outlays worldwide by 2030 to keep up with demand for compute.
That spending encompasses far more than buildings. The AI infrastructure ecosystem includes:
- Graphics processing units (GPUs) and AI accelerators
- High-bandwidth memory
- Servers and storage
- High-speed networking equipment
- Data center construction
- Electricity generation and transmission
- Cooling and thermal-management systems
- Backup power
- Fiber-optic connectivity
- Land and industrial facilities
Individual companies are also committing staggering amounts of capital. Amazon said it planned to increase capital expenditures to approximately $100 billion in fiscal 2025, with the vast majority going toward new data centers and AI infrastructure.
Alphabet reported $91.4 billion of capital expenditure in 2025, with approximately 60% going toward servers and 40% toward data centers and networking equipment.
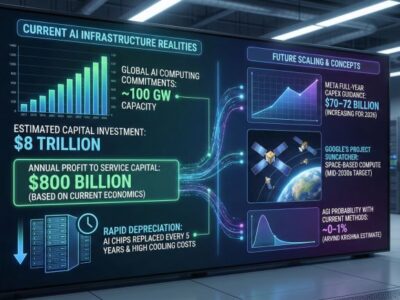
Meta spent $72.22 billion on capital expenditures in 2025 and has indicated that infrastructure spending will remain a major priority as it expands AI capacity.
OpenAI’s Stargate initiative provides an even more dramatic example. The project initially announced plans to invest $500 billion over four years in U.S. AI infrastructure, beginning with $100 billion of deployment.
These figures illustrate why comparisons with the telecom investment boom of the late 1990s have become increasingly common.
What Happened During the Dot-Com Era?
The late-1990s internet boom produced enormous infrastructure investment. Telecommunications companies believed internet traffic would grow rapidly and indefinitely. They invested heavily in long-distance fiber networks, switches and other equipment.
Federal Reserve research shows that capital expenditures by selected U.S. telecommunications service providers increased from approximately $42.4 billion in 1997 to $61.2 billion in 1999 and $75.7 billion in 2000.
The investment created real infrastructure. But demand did not grow quickly enough to support all of it at profitable prices.
One historical analysis cited by the U.S. Securities and Exchange Commission reported that interexchange carriers deployed more than $200 billion in capital to build roughly 60,000 route miles of new fiber. The resulting combination of oversupply, weaker demand and falling prices contributed to financial distress among telecom operators.
The International Monetary Fund later summarized the problem bluntly, stating that “overinvestment had probably occurred” in telecommunications and parts of the information technology sector.
The lesson is important: infrastructure can be economically valuable and still be overbuilt.
Fiber networks eventually became fundamental to the modern internet. But the companies that financed those networks did not necessarily capture the economic value they created.
The Biggest Similarity: Build First, Monetize Later
The strongest similarity between the two eras is the willingness to invest ahead of proven demand. During the dot-com boom, telecom companies built networks based on expectations of future internet traffic.
Today, technology companies are building computing capacity based partly on expectations of future AI workloads.
This creates a familiar investment equation:
Expected AI demand → more infrastructure → lower computing costs → more AI applications → greater demand for infrastructure.
The cycle can become self-reinforcing. However, it can also reverse.
If AI applications fail to generate sufficient economic value, customers may reduce spending. Data centers could then become underutilized, while companies continue paying for power, leases, debt and equipment.
This is precisely the type of infrastructure risk that appeared in telecom after 2000.
Why the AI Boom Is Different
Despite the similarities, calling AI infrastructure simply “the next dot-com bubble” misses several important differences.
1. AI has real revenue today
Many dot-com businesses had limited revenues, weak business models or no clear path to profitability. AI is different.
Cloud providers already sell AI computing. Enterprises are paying for AI software. Consumers are using AI products. Semiconductor companies are generating enormous revenues from AI-related demand. The infrastructure therefore supports an existing commercial market rather than a purely hypothetical one.
2. Today’s biggest investors are financially stronger
A significant portion of AI infrastructure spending is being made by companies such as Amazon, Alphabet and Meta. These companies have substantial operating businesses generating cash.
That does not eliminate investment risk, but it makes the financing structure different from the highly leveraged telecom boom.
The dot-com-era telecom sector was particularly vulnerable to debt and capital-market conditions. The IMF noted that leverage in telecommunications and energy amplified the technology bubble.
3. AI hardware becomes obsolete much faster
This is both an opportunity and a risk. Fiber-optic cables can remain useful for decades. AI accelerators may become economically obsolete much faster as new generations deliver better performance per dollar and per watt.
Alphabet, for example, reported that its 2025 infrastructure spending was split roughly 60% toward servers and 40% toward longer-duration data centers and networking assets.
That means AI infrastructure requires continuous reinvestment. A data center may last decades, but the chips inside it may need replacement much sooner.
The Capital Spending Comparison
The following table highlights the fundamental difference between the two cycles:
| Metric | Dot-Com/Telecom Boom | AI Infrastructure Boom |
|---|---|---|
| Selected U.S. telecom capex, 1999 | $61.2B | — |
| Selected U.S. telecom capex, 2000 | $75.7B | — |
| Amazon 2025 capex | — | ~$100B |
| Alphabet 2025 capex | — | $91.4B |
| Meta 2025 capex | — | $72.2B |
| Stargate announced commitment | — | $500B |
| Estimated global data center investment through 2030 | — | Up to ~$7T |
Sources: Federal Reserve, company disclosures, OpenAI and McKinsey. Figures are not directly comparable because definitions, currencies, companies and geographic coverage differ.
The comparison demonstrates the extraordinary scale of the current cycle—but it should not be interpreted as an apples-to-apples measure of economic overheating.
The Most Important Risk: AI Infrastructure Overcapacity
The biggest danger is not that AI disappears. It is that supply grows faster than profitable demand.
Read Also: Beyond the Hype: What Actually Counts as AI Infrastructure
Consider a hypothetical scenario in which companies collectively build millions of additional GPUs and hundreds of new data centers. If AI usage grows rapidly enough, those facilities could generate attractive returns.
But if model efficiency improves dramatically, AI inference becomes cheaper, or enterprises discover that fewer AI workloads are economically valuable than expected, utilization could disappoint. This is similar to telecom.
The infrastructure itself may survive, but investors and operators can still lose money.
The historical record provides a warning. After the telecom boom, companies shifted from building networks toward improving utilization and returns on existing infrastructure. Contemporary filings described excess network assets, excess bandwidth and high debt as major constraints on capital spending.
A Major Difference: AI Infrastructure Can Create Its Own Demand
There is, however, an important counterargument. AI infrastructure is not merely serving a fixed amount of demand. More computing power can enable larger models, lower prices and entirely new applications.
This creates a potentially powerful feedback loop:
- More chips increase available compute.
- More compute enables better AI models.
- Better models create new applications.
- New applications attract customers.
- Greater usage justifies additional infrastructure.
McKinsey describes compute as one of the decade’s most critical resources, with data center demand projected to rise dramatically as AI adoption expands.
That dynamic did not necessarily operate as strongly in telecommunications. More fiber capacity did not automatically create enough profitable demand to absorb every additional kilometer of network.
What Investors Should Watch
The most useful way to judge whether AI infrastructure investment is sustainable is to monitor returns rather than headlines.
Key indicators include:
- Data center utilization: Are new facilities operating close to capacity?
- Cloud AI revenue: Is AI-related revenue growing faster than infrastructure costs?
- Return on invested capital: Are companies earning attractive returns on new data centers?
- GPU utilization: How intensively are expensive accelerators being used?
- Power availability: Can electricity infrastructure keep pace with data center construction?
- AI software adoption: Are businesses deploying AI at scale?
- Model efficiency: Are advances in algorithms reducing the amount of compute required?
- Financing conditions: Is infrastructure increasingly dependent on debt and complex financing structures?
- Hardware depreciation: How quickly are new AI accelerators making older equipment uneconomic?
These metrics are more informative than simply asking whether AI spending is “too high.”
The Dot-Com Era’s Most Important Lesson
The dot-com crash does not prove that today’s AI infrastructure investment will fail. In fact, one of the greatest lessons of the dot-com era is that a technology can be revolutionary even when its investment bubble is destructive.
The internet transformed communications, commerce, entertainment and business. Fiber networks built during the boom eventually became essential infrastructure for the digital economy.
But investors paid too much for some of that future. The same distinction matters today.
AI could become one of the most important general-purpose technologies of the 21st century while some data centers, AI companies, chip investments and infrastructure projects still produce disappointing returns.
As McKinsey puts it, AI is creating an enormous demand for compute, but “future demand [is] uncertain,” meaning investors must make calculated infrastructure decisions.
Conclusion
AI infrastructure investment resembles the dot-com era in three major ways: enormous capital commitments, expectations of explosive future demand and the risk of building capacity faster than profitable usage develops.
But the differences may be even more important.
Today’s AI boom is being financed substantially by profitable technology companies, supported by established cloud businesses and driven by customers already paying for AI services. At the same time, AI hardware has unusually rapid upgrade cycles, making the investment more recurring—and potentially more economically demanding—than the fiber boom of the 1990s.
The ultimate outcome will probably be more nuanced than “AI bubble” versus “AI revolution.”
Some infrastructure will generate exceptional returns. Some will become stranded or underutilized. Some companies will capture enormous value, while others will spend billions only to discover that technological progress has made their investments less competitive.
The dot-com era therefore offers a valuable warning rather than a direct prediction.
The key question is not whether AI infrastructure is necessary. It is whether the economic value generated by AI will grow fast enough to justify the extraordinary amount of capital being committed today.
FAQ
Is AI infrastructure investment another dot-com bubble?
Not necessarily. AI investment shares similarities with the dot-com era, including rapid capital spending and high expectations, but AI already generates significant commercial revenue and demand.
How much are companies investing in AI infrastructure?
Investment is reaching extraordinary levels. Major technology companies are committing tens of billions of dollars annually to data centers, servers and AI computing, while global data center investment could reach trillions of dollars by 2030.
What is the biggest risk of AI infrastructure investment?
The biggest risk is overcapacity. If AI demand or revenue grows more slowly than expected, companies could end up with expensive data centers and computing equipment that generate inadequate returns.
What can investors learn from the dot-com era?
The dot-com era shows that a transformative technology can succeed even when some investments fail. Investors should focus on utilization, revenue growth, profitability and returns on infrastructure rather than assuming every AI-related investment will succeed.
Source: linkedin.com




Comments