
 By
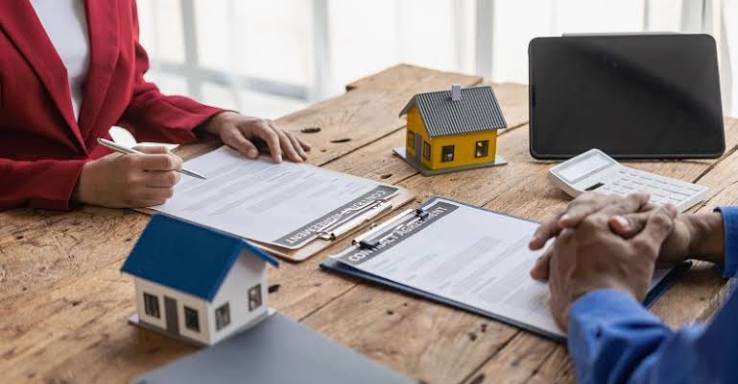
Investing in US real estate requires treating the process as a business. Key steps involve securing financing tailored to rental properties (which often requires larger down payments), targeting high-demand neighborhoods, performing strict tenant screening, and ensuring compliance with local landlord-tenant laws.
1. Research and Target the Right Location
- Cash Flow vs. Appreciation: Decide if you want immediate monthly cash flow or long-term property value growth. Look for areas with growing job markets, good school districts, and planned infrastructure developments.
- Property Taxes: US property taxes vary wildly by state and county (e.g., New Jersey has high rates; Hawaii has low ones). Always factor this into your monthly expenses.
2. Secure the Right Financing
- Investment Loans: Traditional mortgages are for primary residences. For an investment property, you will typically need a dedicated buy-to-let mortgage, which generally requires a minimum down payment of 20% to 25%.
- Get Pre-Approved First: Work with local or national lenders to understand your purchasing power and lock in interest rates before house-hunting.
3. Screen Tenants Thoroughly
- Background Checks: Utilize tenant screening services to check credit history, criminal records, and eviction histories.
- Verify Income and References: A good rule of thumb is to ensure the tenant’s gross monthly income is at least 3 times the monthly rent. Always contact their previous landlords.
4. Understand Rental Laws (Landlord-Tenant Acts)
- Local Compliance: Each US state and city has specific laws dictating security deposit limits, eviction processes, and habitability standards.
- Fair Housing Act: Ensure your marketing and tenant selection do not violate the federal Fair Housing Act, which prohibits discrimination based on race, color, national origin, religion, sex, familial status, or disability.
5. Consider Professional Property Management
- Offload the Burden: If you are not local to the area or prefer a hands-off approach, consider hiring a property management company. They typically charge 8% to 12% of the monthly rent but handle marketing, tenant placement, rent collection, and maintenance calls.
6. Budget for the Unexpected
- Maintenance Fund: Expect to spend about 1% of the home’s value annually on upkeep.
- Vacancy Rate: Account for periods when the property is empty. A safe buffer is to budget for 1 to 2 months of lost rent each year.
Buying rental real estate can be a great investment opportunity. Below we explain some of the steps you may take to tap into that market:
Identify your preferred rental property area or neighborhood
To determine the right rental property to invest in, start by narrowing down the neighborhoods that work best for your investment strategy. This may mean identifying which neighborhoods will help you increase the value of your property — instead of detracting from it.
Read Also: Few Tips On Refinancing Home Mortgages
Look at the following qualities for neighborhoods:
- School district
- Employment rates
- Rent rates
- Rental vacancy rates
- Crime rates
- Public transportation options
- Property tax rates
- Proximity to value-add amenities (e.g., parking, grocery stores, shopping centers, etc.)
Identify the rental property you should buy
After choosing your ideal areas, look for a rental property that best suits your investment needs. Here are a couple of recommendations to follow when buying rental property (assuming they meet your investment strategy):
- Pay extra attention to vacancy rates. You need tenants to make an investment property work. That’s why it’s important to keep an eye on vacancy rates; some locations have lower vacancy rates than others.
- Research average rents. If your investment strategy revolves around generating a positive ROI, then it’s key to understand each area’s average rent.
- Potential development. Is the rental property going to be near future development and/or construction? This can be a sign of growth, which is beneficial to the property value. You can check in with the local municipal planning department to verify what plans have zoned into the area.
Research and estimate return on investment (ROI)
Many believe the key to successful investment rental property is if it makes you money. Some investors will tell you if it doesn’t positively generate ROI (the financial metric that determines how profitable an investment property might be), the rental property isn’t worth buying. Depending on your investment strategy this may be true but many investors have also been successful with purchasing property with a negative ROI. But how do you estimate your potential ROI?
First, you need to have the below estimations:
- Annual rental income
- Annual operating expenses (e.g., taxes, insurance, repairs, etc.)
- Rental property investing costs (e.g., down payment, loan costs, etc.)
An investor who is focused on ROI should calculate the property’s net annual income before buying rental property. This is the remaining amount after taxes, insurance, expected repairs, potential vacancy periods and utilities not covered by tenants. If applicable, you’ll also need to subtract property management costs, homeowner association (HOA) fees and any other unique expenses.
Once you have the net annual income, divide it by the amount you spent on the property. Below is an example:
Net annual income / Amount invested in rental property = ROI
$10,000 / $100,000 = 10% ROI
The ROI calculation will help new investors understand whether a property is a good investment if their focus is to generate a positive ROI.
If you need help calculating potential rent for a property, use AAOA’s prorated rent calculator to determine an estimated rental income.
Obtain financing
Oftentimes, people may be hesitant to purchase a property to rent due to the associated costs. They may be reluctant to use their savings to complete the real estate investment or they may not have the disposable income needed. Even if the necessary money is available, taking that final step of making a down payment may take some extra courage for a first-time investment buyer.
However, you don’t have to empty your savings or take a hard hit to your bank account. Even if you’re capable of purchasing an investment property with cash, it may still be beneficial to get a mortgage. One such case would be if you intend to purchase multiple investment properties instead of just one.
When buying a property, you need to know how much you can afford. If you’re unsure how to determine this amount, take a look at a mortgage calculator. A mortgage calculator will show you examples of rates and monthly payments, which you can use to determine your budget.
You should also factor in rental income when buying a rental property — this is where you can consider the 1% rule. According to Rocket Mortgage, the 1% rule “measures the price of the investment property against the gross income it will generate.” This means the total monthly rent must be either equal or more than 1% of the property purchase price.
It’s important to understand that the 1% rule can be helpful, but it’s not an indicator of whether or not your investment is successful. This depends on your personal goals as an investor.
Conclusion
To prevent future headaches, it’s best to ensure that all necessary documents the IRS may require are in order. Below are three tips to keep your rental property financial documents organized:
- Keep all documents, receipts and records in one, centralized location. This guarantees that everything you need as a rental property owner is easily accessible.
- Consistently update and maintain these items. As a best practice, don’t try to locate and organize expense items at the last minute (or right before tax day!).
- Separate your personal finances from rental property finances. Your business has different expectations, regulations and qualifications. Open a separate bank account and credit cards to make tracking your finances easier.
If you want to go the extra mile to make things easier for yourself, take some time to get to know IRS tax form 1040, Schedule E. This is the form that you will submit to the IRS at the end of the year for your rental property.
However, if you’ve hired a property management company, these expense responsibilities will be tracked and taken care of by them. When tax season begins, they should send you the documents you need to submit to the IRS.



Comments