
 By
Fintech is transforming financial inclusion in Africa by enabling the unbanked and underbanked to have access to banking, payments, and credit using mobile technology. Fintech platforms enable financial services in remote locations and empower small enterprises by leveraging accessible tools such as USSD codes and smartphone apps, as well as digital lending and alternative credit scoring systems that utilize non-traditional data. This is reshaping communities by promoting economic growth and decreasing inequality in areas where traditional financial infrastructure is inadequate.
How Fintech is driving financial inclusion
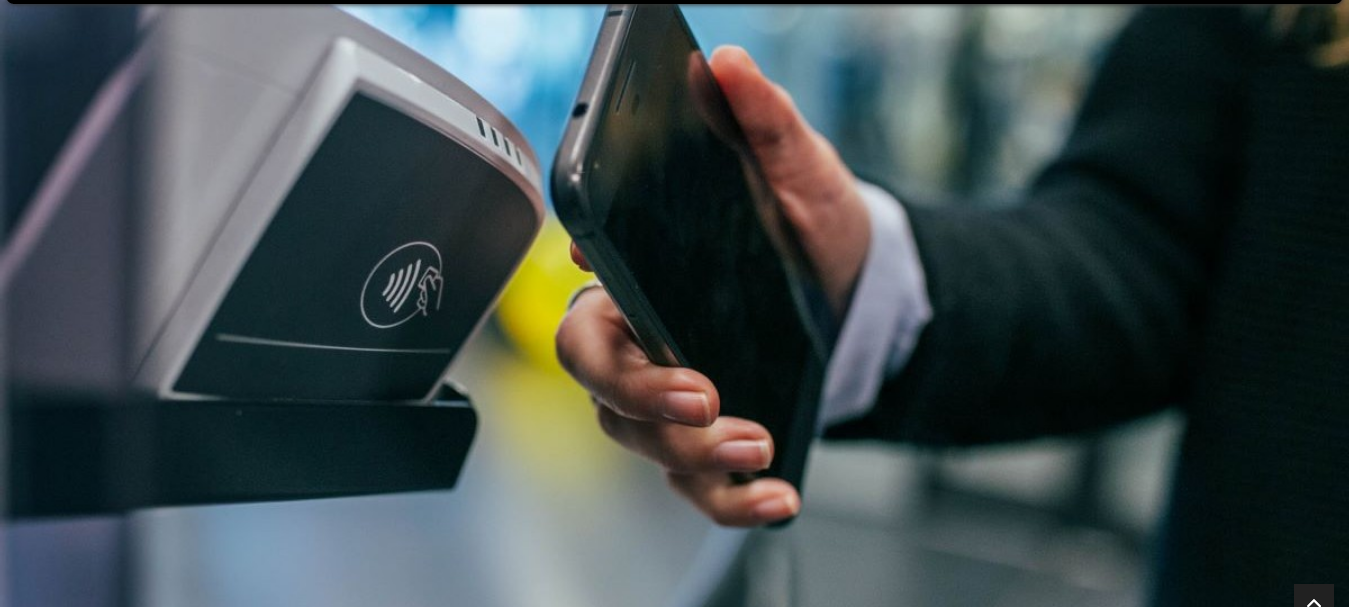
- Mobile money and payments: Services like M-Pesa and OPay have made it possible to send and receive money, pay bills, and receive wages via mobile phones, even in remote areas. This has led to mobile money accounts surpassing traditional bank accounts in some countries.
- Digital lending: Fintech companies are using alternative data, such as social media activity and mobile phone usage patterns, to assess creditworthiness for individuals and small businesses that lack traditional credit histories. This allows them to access small loans for business or personal needs.
- Accessible platforms: Fintechs use both simple USSD codes and user-friendly smartphone apps to provide financial access, making it convenient for a wide range of users.
- Localized solutions: Fintech companies are tailoring products to meet specific cultural and economic needs across different regions, ensuring that the services are both relevant and impactful.
- Reduced costs and increased efficiency: By cutting out intermediaries and using digital platforms, fintechs can offer services at a lower cost, which makes them more affordable for low-income populations.
- New avenues for savings and investment: Fintech platforms allow for safe and confidential savings, and innovative investment opportunities, such as the M-Akiba retail infrastructure bond in Kenya, are accessible via mobile phones.
Impact on Individuals and Businesses
- For individuals: Fintechs provide access to a full range of financial services, including payments, savings, credit, and insurance, empowering individuals who were previously unbanked.
- For small businesses: Fintechs are vital for small businesses, providing them with access to credit and new digital markets, which helps them to grow and thrive.
- For women and rural communities: Fintech has significantly lowered barriers for women and rural populations, who are often excluded from traditional banking services.
- For the economy: By enabling financial inclusion, fintech is helping to reduce inequality and foster a more inclusive economy that can lead to significant economic growth for the continent.
Advantages of FinTech in Financial Services
The rise of FinTech has resulted in a dramatic transformation of the financial industry that benefits consumers, businesses, and financial institutions alike. Some of the main advantages for consumers include:
- Speed and Efficiency
Traditional banking often involves lengthy procedures that can frustrate customers and lead to delays. In contrast, FinTech solutions offer instantaneous experiences, allowing for rapid fund transfers, swift loan approvals, immediate access to account information, etc. This enhanced speed not only improves customer satisfaction but also enables businesses to operate more efficiently and respond quickly to market demands.
- Personalization of Experiences
The demand for personalized financial services is rising. Research indicates that a significant percentage of banking consumers – 70% – consider personalization to be a critical factor in their banking experiences. FinTech companies harness data analytics to tailor products and services to individual customer preferences, ensuring that users receive relevant offerings that meet their unique needs.
- Affordability of Banking Services
FinTech is reshaping consumer expectations regarding the cost of banking services. According to the World Retail Banking Report 2022 by Capgemini and Efma, a notable 75% of surveyed customers are drawn to the cost-effective and seamless solutions provided by FinTech firms. This trend is pushing traditional banks to reevaluate their pricing structures and enhance their service offerings to remain competitive. As a result, consumers benefit from lower fees and improved access to financial services.
- Financial Literacy and Empowerment
FinTech is playing a significant role in accelerating financial literacy in both developing and developed countries. This is achieved through various digital platforms and tools that provide accessible resources, such as budgeting apps, webinars, podcasts, and other educational content, which have become increasingly available in the modern age of FinTech.
- Increased Accessibility of Financial Services
FinTech has significantly improved access to financial services, particularly in underserved regions where access to traditional banks is limited. FinTech solutions, such as mobile apps, allow customers to access a full range of banking services from the comfort of their homes, breaking down the geographical barriers that have traditionally hindered access to banking services.
The Future of FinTech
As we look ahead, the digital financial industry is primed for even more transformational shifts, with the potential to restructure the whole financial sector. One of the important trends predicted to dominate the financial industry is the continuing incorporation of emerging technologies such as artificial intelligence, machine learning, and blockchain.
Read Also: Nigeria’s Digital Economy Strategy: Progress and Pitfalls
These technologies will help FinTech companies create more intelligent, tailored, and secure financial services. AI-powered financial advisors, for example, may make highly personalized investment suggestions based on a client’s specific financial profile and risk tolerance. In contrast, blockchain-based platforms have the potential to transform cross-border payments, trade finance, and digital asset management by providing faster, more secure, and transparent financial transactions.
Another trend that is expected to influence the future of FinTech is a greater emphasis on financial inclusion and accessibility. FinTech companies are already playing an important role in delivering financial services to underbanked and disadvantaged communities, and the trend is projected to continue. FinTech enterprises can provide vital financial tools and resources to those who have previously been excluded from the official financial system by utilizing mobile technology, alternative credit scoring methodologies, and innovative product design.
Conclusion
The FinTech revolution is well underway, and its effects on the financial services industry are apparent. It has radically changed the way we engage with money by opening up new digital channels and options for better financial management. Given the global increase in smartphone and internet penetration, innovations such as mobile banking have become huge game changers. These developments have not only improved client convenience, but have also democratized access to financial services, allowing a wider range of people to engage in the economy.
To continue driving growth, financial institutions, fintechs, government bodies, and other sector actors must collaborate to build an ecosystem that encourages innovation and collaboration. This collaboration will promote innovation, handle regulatory difficulties, and safeguard consumers, paving the way for a more resilient and secure financial system.




Comments