
 By
What are the best low-risk ways to generate compound wealth? Start by eliminating high-interest debt, build an emergency fund in an insured savings account, use certificates of deposit, consider government securities, invest regularly in diversified low-cost index funds, maximize tax-advantaged retirement accounts where available, reinvest dividends and interest, automate contributions, and diversify and rebalance your portfolio over time.
The nine strategies are:
- Pay off high-interest debt
- Use high-yield savings accounts for cash reserves
- Build a CD ladder
- Consider government bonds and Treasury securities
- Invest in diversified low-cost index funds
- Maximize tax-advantaged retirement accounts
- Reinvest dividends and interest
- Automate contributions with dollar-cost averaging
- Diversify and rebalance for long-term compounding
There is one important clarification: low risk does not mean no risk.
Bank deposits may have inflation risk. Bonds can lose market value before maturity. Stock index funds fluctuate, sometimes dramatically. Even apparently conservative investments can lose purchasing power.
The goal is therefore not to eliminate every risk. It is to pursue reasonable returns while controlling unnecessary risk and giving compound growth enough time to work.
Investor.gov describes compound growth as earning returns on both your original investment and the returns the investment has already generated. Its simple formula for long-term wealth is:
“regular investments + time → wealth.”
9 Compound-Wealth Strategies Compared
| Strategy | Relative Risk | Main Purpose | Compounding Potential |
|---|---|---|---|
| Pay high-interest debt | Very Low | Stop negative compounding | High indirect benefit |
| High-yield savings | Very Low* | Emergency reserves | Low–Moderate |
| CD ladder | Very Low* | Predictable interest | Low–Moderate |
| Government securities | Low | Income/capital preservation | Low–Moderate |
| Diversified index funds | Moderate | Long-term growth | High |
| Retirement accounts | Depends on investments | Tax efficiency | High |
| Reinvest income | Depends on asset | Accelerate compounding | High |
| Automated investing | Depends on asset | Consistency | High |
| Diversification | Varies | Risk management | Supports long-term growth |
*When held with appropriately insured institutions and within applicable insurance limits.
1. Pay Off High-Interest Debt First
The first compound-wealth strategy may involve stopping compounding from working against you. Credit-card interest can accumulate quickly.
Suppose you have $5,000 of debt charging 20% annual interest. Meanwhile, you’re investing money hoping to earn 7%. Mathematically, eliminating the expensive debt may provide a stronger financial benefit than pursuing uncertain investment returns.
The U.S. Securities and Exchange Commission’s Investor.gov advises:
“No investment will give you guaranteed returns to outweigh the high interest rate you pay with a credit card.”
It recommends controlling credit-card debt as an early step toward building wealth. Before chasing investment returns, eliminate financial leaks.
2. Keep Emergency Money in High-Yield Savings
An emergency fund isn’t designed to make you rich. It is designed to stop unexpected expenses from destroying your wealth-building plan.
If your car breaks down or you unexpectedly lose income, cash reserves can reduce your need to sell investments or borrow at high interest rates.
And cash can still earn interest.
As of September 2026, the U.S. national average savings yield was approximately 0.38%, while some high-yield savings accounts were offering rates around 4% or higher. Rates change frequently and availability depends on institution and eligibility.
For a $10,000 emergency fund, the difference between 0.38% and 4% is substantial:
0.38% = approximately $38 annual interest
4% = approximately $400 annual interest
before considering compounding and assuming rates remained unchanged. Don’t chase yield at the expense of deposit protection, liquidity or account terms.
3. Build a CD Ladder
Certificates of deposit can provide predictable interest in exchange for committing money for a specified period. Instead of locking $20,000 into one five-year CD, you could divide it across multiple maturity dates.
For example:
- $5,000 → 6-month CD
- $5,000 → 12-month CD
- $5,000 → 18-month CD
- $5,000 → 24-month CD
As each matures, you can spend it if necessary or reinvest it. This is known as CD laddering.
As of September 18, 2026, the average U.S. 12-month CD APY was reported at approximately 1.71%, while some leading offers were substantially higher. Rates will change, so compare current terms, penalties and deposit protection before investing.
4. Consider Government Securities
Government securities can form the conservative part of a wealth-building portfolio. In the United States, Treasury bills mature in one year or less, while Treasury notes currently come in 2-, 3-, 5-, 7- and 10-year terms.
Read Also: The best Wealth Creation strategies for Financial Success
Treasury notes pay fixed interest every six months and can currently be purchased in increments starting at $100.
Other countries issue their own government securities.
The attraction is generally lower credit risk relative to many private issuers.
But remember:
Low credit risk ≠ zero investment risk.
Inflation can reduce purchasing power, and longer-term bonds can fluctuate in market value if sold before maturity.
5. Use Diversified, Low-Cost Index Funds for Long-Term Money
This is where the definition of “low risk” needs care. Stock index funds are not low-risk over short periods. They can fall sharply during market downturns.
For long investment horizons, however, broad diversification can reduce the company-specific risk associated with owning only a handful of individual stocks.
FINRA says traditional index funds offer exposure to a broad basket of securities and generally carry less risk than investing in individual securities.
Investor.gov notes that some experts use 7%–10% annual returns as a historical long-term estimate for diversified U.S. stock investments, but this is not a guaranteed future return.
Consider the hypothetical effect of $500 invested monthly at 7%:
| Time | Contributions | Approx. Value |
|---|---|---|
| 10 years | $60,000 | $86,500 |
| 20 years | $120,000 | $260,000 |
| 30 years | $180,000 | $610,000 |
| 40 years | $240,000 | $1.31 million |
These are mathematical illustrations assuming steady 7% annual returns with monthly compounding, not predictions. Actual market returns fluctuate and fees and taxes would affect results.
6. Maximize Tax-Advantaged Accounts
Taxes can interrupt compounding. Where available, retirement and investment accounts offering tax advantages can allow more money to remain invested.
For U.S. investors, examples include 401(k)s and IRAs. Other countries have different pension and tax-advantaged investment structures.
Investor.gov specifically recommends considering workplace retirement accounts and notes that some employers match employee contributions.
It describes employer matching as:
“free money!”
Before investing through any retirement account, understand withdrawal rules, taxes, investment choices and fees.
7. Reinvest Your Dividends and Interest
Compound wealth becomes much more powerful when investment income isn’t immediately spent. Imagine an investment generates $500 of dividends.
You have two choices:
Spend $500
or:
Reinvest $500 so it can potentially generate future returns itself.
That creates the cycle:
Capital → Return → Reinvestment → Larger capital base → More potential returns
This is the essence of compounding.
Reinvestment doesn’t guarantee profits because asset values and dividends can fall. But continually removing every dollar of investment income limits the capital available to compound.
8. Automate Investing With Dollar-Cost Averaging
Trying to identify the perfect moment to invest can lead to procrastination. Dollar-cost averaging offers a simpler approach.
Investor.gov defines it as investing equal amounts at regular intervals “regardless of the ups and downs in the market.”
For example:
Payday → Automatically invest $300
Next payday:
Another $300
Continue through good markets and bad markets. When prices are lower, the same contribution purchases more units; when prices are higher, it purchases fewer.
Investor.gov specifically encourages automating retirement contributions so wealth building happens each time you’re paid rather than requiring repeated decisions.
Automation turns investing from an occasional intention into a financial system.
9. Diversify and Rebalance
The final strategy protects the compounding engine. Don’t concentrate everything in:
one stock, one industry, one property, one cryptocurrency or one speculative investment.
FINRA summarizes diversification with the classic phrase:
“Don’t put all your eggs in one basket.”
A diversified portfolio might contain different proportions of:
Cash + Bonds + Domestic stocks + International stocks
depending on your circumstances, risk tolerance and time horizon.
Diversification cannot prevent all losses, but Investor.gov says it can improve the chances that losses are smaller than they might have been without diversification.
Periodically rebalancing helps return the portfolio to its intended risk level.
The Mathematics of Compound Wealth
Compounding becomes increasingly powerful with time.
Investor.gov provides a striking example for a hypothetical $1 million retirement target at age 65, assuming a 7% average annual return:
| Starting Age | Approx. Monthly Investment Needed |
|---|---|
| 18 | $254 |
| 25 | $418 |
| 35 | $883 |
| 45 | $2,033 |
| 55 | $6,032 |
These figures are illustrations rather than guaranteed outcomes.
The lesson isn’t that everyone will earn 7%.
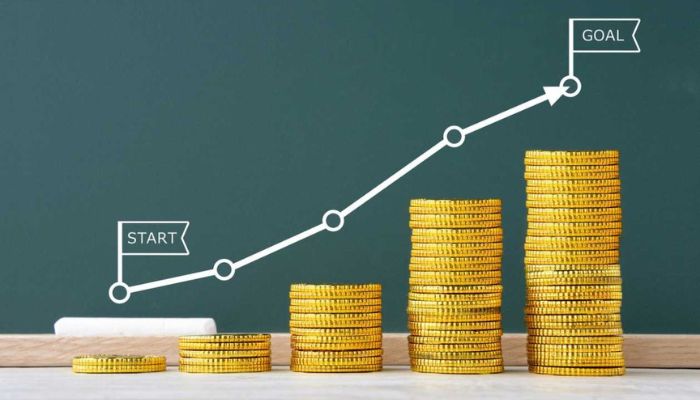
It’s that time can dramatically reduce the amount of money required from your pocket because earlier contributions have longer to compound.
Bottomline
Generating compound wealth isn’t primarily about finding an investment that suddenly makes you rich. It is about building a financial system that can operate for decades.
Start with:
Eliminate expensive debt → Build emergency reserves → Invest regularly → Diversify → Reinvest returns → Keep fees low → Repeat
Investor.gov’s historical illustration shows just how important starting early can be: under its hypothetical 7% return assumption, someone beginning at 25 would need approximately $418 monthly to target $1 million at 65, while starting at 45 raises the illustrative requirement to more than $2,000 monthly.
That’s the real secret of compound wealth. You don’t necessarily need the highest return. You need a reasonable return, controlled risk, regular contributions—and enough time for your money to start earning money on the money it has already earned.
FAQ
What is the safest way to build compound wealth?
There is no universally safest strategy because risk depends on your goals, country, time horizon and financial circumstances. Insured deposits and high-quality government securities can provide greater capital stability, while diversified investments provide more long-term growth potential with greater price volatility.
How much money do I need to start?
You don’t necessarily need thousands. Investor.gov emphasizes regular investing over time, and U.S. Treasury notes currently have a $100 minimum purchase.
Is compound wealth guaranteed?
No. Compound mathematics is predictable when the return is fixed, but investment returns aren’t. Stocks, funds and bonds can fluctuate, while savings rates change and inflation reduces purchasing power.
Source: investor.gov




Comments