
 By
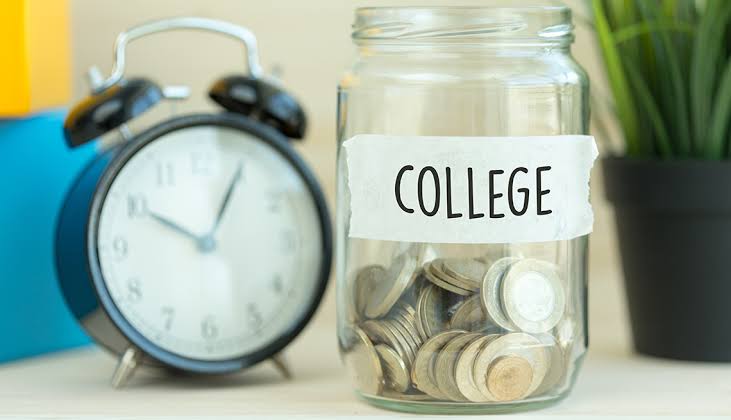
To determine how much to save for college, you can use three practical strategies: the One-Third Rule to cover a portion of total costs, the Age-Based Target for consistent, long-term saving, or a Percentage of Income method to fit savings naturally into your existing budget.
1. The One-Third Rule
This strategy, often cited by financial planners, aims to cover about 1/3 of the projected future cost of a bachelor’s degree. It assumes the remaining costs will be paid through current income while the student is in school, financial aid (scholarships/grants), and modest student loans.
- How it works: Multiply the total expected cost of your preferred institution by 0.33, then divide by the number of years until the student enrolls to find your target annual savings.
2. The Age-Based Monthly Target
If you begin saving from birth, you can break your goal into manageable monthly contributions that ideally cover about one-third of tuition. According to Saving for College, your ideal monthly savings targets from birth to enrollment should be:
- In-state public: Save at least $170 per month.
- Out-of-state public: Save at least $300 per month.
- Private non-profit: Save at least $485 per month.
3. The Percentage of Income Method
If you are starting later or prefer a budget-driven approach, save a set percentage (typically 5% to 10% of your gross household income.
- How it works: Evaluate your current income and deduct this percentage into dedicated tax-advantaged accounts like a 529 Plan. This ensures that saving for higher education grows alongside your income and scales with your family’s financial reality.
Below are 3 keys strategies you can use:
Choose an End Goal
One of the most common ways to set a savings goal is based on the projected cost of college. It helps to start by using one of the calculators out there to help you estimate the cost of college for your child, based on factors like your child’s age, the type of school you expect your child to attend, and the expected rise in the cost of college. You should also consider whether there is a specific school that you already know your child wants to attend.
Getting a little sticker shock? The good news is that whether you’re saving for in-state, out-of-state, or private, you don’t have to plan for the whole amount.
Financial advisors might instead recommend saving between one-third and 50% of the cost of college, with the expectation that the rest will come from financial aid, scholarships, and current parent and/or student income. This can make the goal of saving for college feel more realistic and achievable.
For example, let’s that you just had a child and you’re ready to start saving now. In order to pay a third of the projected cost of college, your end goal might be $40,000 for a public in-state university, $61,000 for a public, out-of-state school, and $75,000 for a private college.
Set a Monthly Goal
Is it a little too difficult to imagine the end goal, years from now? Consider walking it back to a monthly contribution amount. Just remember that how you save will make a big impact on how much you save by the time your child starts college.
Read Also: How To Get Money For College Tuition
Many experts recommend using a 529 college savings plan, a tax-advantaged investment account. A 529 plan offers tax-free growth and withdrawals for qualified higher education expenses, which include tuition and fees, room and board, books, computers, and special education expenses.
What does this mean for you? Choosing a 529 plan could mean a much lower monthly contribution since the money grows over time. With a 529 plan, a solid monthly contribution amount for a child born in 2024 would be about $140 for a public in-state school, $215 for public out-of-state, or $350 for a private university.
If you intend to save using a traditional savings account or a taxed investment account, you’ll want to adjust your monthly contribution accordingly. For example, the average interest rate on savings accounts as of September 2024 is just 0.46% APY (annual percentage yield). At that rate, in a savings account, you’d need to contribute about $180 per month for 18 years to pay for a third of the projected cost of a public, in-state college; around $270 for out-of-state; and around $330 per month for a private university. Much more than the required savings compared to a 529.
Using a taxed investment account can yield significantly better returns on your savings. With an average 7% return, a monthly contribution of about $95 would cover the projected cost of a public in-state university, $140 for out-of-state, or $175 for a private college. However, you will miss out on the 529 plan’s tax exemptions on dividends and gains.
Determine What You Can Afford
Lastly, you can set a monthly savings goal for college based on what your family can afford. This is a good approach if there’s not much wiggle room in your budget.
Of course, what’s affordable will vary widely from one family to the next. If you’re not sure what’s doable for your family, try breaking it down using the Lumina Foundation’s Rule of 10 formula.
Though originally intended as a benchmark for colleges seeking to expand access to higher education, the formula can certainly be utilized by families. This approach recommends that families pay for college using the benchmarks:
- Families save 10% of their discretionary income
- Families save over a period of 10 years
- Students work 10 hours per week while attending college
Discretionary income is typically defined as total after-tax income, minus all minimal survival expenses such as food, medicine, housing, utilities, insurance, transportation, and so on.
However, the Lumina Foundation states that for the purposes of these benchmarks, any income above 200% of the federal poverty level is “discretionary.” For a family of four in 2024, that would be any income over $62,400.7
Following this formula, a family making an average of $100,000 annually might save 10% of the remaining $37,600, or $376 per month. Over 10 years, that’s more than $45,000 saved for college. With a student working 10 hours per week for 50 weeks per year at the current $7.25 minimum wage, that’s an additional $3,625, for a total contribution of $14,500 over four years.
Of course, if your income increases or decreases, your contributions can be adjusted accordingly. And you can always make this methodology go further by using a tax-advantaged savings tool to grow your money over time.
For example, if a family with an 8-year-old child began saving $445 per month in a 529 savings plan, that amount would grow to be enough to cover a third of the costs that experts recommend for a public-out-of-state school, or about half the cost of an in-state university.
Final Thoughts
While it’s easy to get sticker shock from skyrocketing college costs, remember that the amount you need to save is likely much lower. The important thing is to start as early as possible and to be consistent with saving. However, if your child is older, don’t panic—you can still save a significant amount in a shorter time frame.
Financial aid, scholarships, student work, your income while your child is attending college, and contributions from family can all help to make up the rest.





Comments